
July Jobs Land at 11:30 as Discretionary Retail Cracks and Roy Morgan Tips a $40 Billion August. | It s On Sale Daily Brief, 20 August 2026

Thursday is jobs day for Australian households. The ABS releases the July Labour Force Survey at 11:30am AEST, the single biggest data point ahead of the RBA 22 to 23 September meeting, with June s 4 point 4 per cent unemployment and 76,300 job surge as the baseline. The Sydney Morning Herald reports the consumer discretionary index has fallen more than 5 per cent in the past five days as JB Hi-Fi CEO Nick Wells warns he sees no signs of consumer recovery. Solomon Lew has shut all three Peter Alexander UK stores and cut Premier FY26 profit guidance to 176 million dollars. Roy Morgan tips August retail to hit a record 40 billion dollars. Today s Top 5 opens with Mossman at 70 per cent off, then Hallensteins, Healthy Life, House and Macpac.

Jobs Day: The ABS July Labour Force at 11:30 is the RBA September Pivot

At 11:30am AEST the ABS releases the July 2026 Labour Force Survey, and this is the print the Reserve Bank has been waiting for since the June result. The June baseline set an aggressive bar: unemployment at 4 point 4 per cent (up 0 point 1 percentage points from May s rounded 4 point 3), employment plus 76,300 (the strongest print since April 2025 and led by plus 47,000 part time), participation at 67 per cent (a one year high) and underemployment at 6 point 5 per cent (the highest since August 2024). Reuters summed up the market reaction: bond yields snapped higher and rate cut bets thinned, but not enough to remove the September cut from money market pricing.

Westpac IQ s July preview expects unemployment steady at 4 point 4 per cent, employment plus 15,000 and participation at 66 point 9 per cent. Any soft print (unemployment above 4 point 5 per cent, or employment below plus 5,000) would sharpen September rate cut expectations and typically translates within four weeks into deeper Everyday Rewards, Flybuys and MYER one targeted offers. Any strong print (unemployment 4 point 3 or lower) would push the cut into November and floor set discount depth for spring collections would narrow. Diarise 11:30 in your app of choice, this one flows straight into the mortgage and the retail promotion calendar.

Retailers on the Ropes: JB Hi-Fi Sees No Recovery, Discretionary Down 5 Per Cent in Five Days

Consumer discretionary retailers are having a very rough week. The Sydney Morning Herald reports that over the past five days the ASX consumer discretionary index has fallen more than 5 per cent compared with the ASX200 which is 1 point 7 per cent softer, with earnings misses and downgrades from Premier Investments, Beacon Lighting, JB Hi-Fi and Baby Bunting driving the sell off. JB Hi-Fi CEO Nick Wells told the market he is seeing no signs of consumer recovery as the combined impact of higher interest rates and the reversal in the nation s runaway property market post Budget make shoppers nervous.

The pattern is a two speed retail sector: staples and hardware are holding up (Coles, Woolworths, Bunnings, Kmart all reporting next week), while discretionary categories from fashion to electronics to homewares are cracking. For Australian shoppers this dynamic means one thing: winter to spring floor set changeovers this week are running deeper discounts than a typical August, particularly across women s wear, footwear and homewares. That is why today s Top 5 has three categories over 50 per cent off and Mossman leading at 70 per cent.

Solomon Lew Shuts Peter Alexander UK, Cuts Premier FY26 Guidance

Premier Investments announced on 12 August the closure of all three Peter Alexander UK stores at Bluewater, Stratford and White City after less than two years, becoming the latest Australian retailer to retreat from the tough British market, per the Australian Financial Review. Chairman Solomon Lew said discretionary retail conditions had deteriorated in the second half and that the group would channel Peter Alexander growth capital into Australia and New Zealand instead. Peter Alexander will keep selling to UK customers online.

The trading update also cut FY26 guidance. Premier Retail full year sales came in at 795 point 5 million dollars (down 2 per cent on FY25) and underlying EBIT guidance was revised down to approximately 176 million dollars (from the 183 million target set in March 2026), per Yahoo Finance. A separate Heads of Agreement was announced for Peter Alexander to return to Myer as a concession partner across 24 stores, per Stockwirex coverage. For sleepwear shoppers watching Peter Alexander pricing, expect the UK inventory clearance to feed into Australian promotions through late August and September.

Amazon Back In Court: Two Live Federal Matters

The Australian Competition and Consumer Commission has two live Federal Court proceedings against Amazon that will bear on Australian Prime subscribers and marketplace shoppers through 2026 and 2027. The first, filed in June 2026, alleges Amazon Australia included five unfair contract terms in Prime subscription contracts with more than one million annual subscribers between November 2023 and August 2025, and relied on those terms to introduce advertising to Prime Video in July 2024, requiring subscribers to pay an additional 2 dollars 99 per month to remain ad free. The case is tracked by the Australian Financial Review, with maximum penalty per contravention the highest of 50 million dollars, three times the benefit obtained, or 30 per cent of adjusted turnover during the breach period.

The second proceeding, filed 29 May 2026 as NSD905 of 2026 in the Federal Court New South Wales Registry, is the first time the ACCC has taken an online marketplace to Federal Court over a mandatory product safety standard. The ACCC concise statement alleges 41 non compliant Unicorn Toddler Backpacks (containing detachable button battery light up unicorn toys without mandatory warning labels) were sold through amazon.com.au and 267 were held in Amazon s Australian fulfilment centres as of 1 November 2022. The ACCC argues that under section 136 subsection 3 of the Australian Consumer Law, mere possession or control of non compliant goods is enough to put the marketplace itself on the hook. If successful, this reshapes marketplace safety liability for every Fulfilment by Amazon third party seller in Australia.

Week Ahead: Coles Tuesday 25, Woolies Wednesday 26, Wesfarmers Thursday 28

Next week is peak reporting week for consumer facing groups. Coles Group hands down FY26 on Tuesday 25 August (media call 9:15am), with the IG earnings preview tracking consensus around 45 dollar 63 billion in sales, EBIT around 2 dollar 30 billion and final dividend per share around 43 cents (FY26 total DPS around 77 cents). H1 already delivered supermarkets EBIT up 14 point 6 per cent and group EBITDA up 7 point 8 per cent to 2 point 2 billion dollars, but the stock fell 8 point 34 per cent on the day, so watch second half momentum commentary closely.

Woolworths Group follows Wednesday 26 August (see the Woolworths investor page), and Wesfarmers reports Thursday 28 August with Bunnings, Kmart and Officeworks the swing divisions, per the Wesfarmers investor centre. H1 Wesfarmers already showed group revenue up 3 point 1 per cent to 24 point 2 billion dollars and NPAT up 9 point 3 per cent to 1 point 6 billion. All three groups use FY presentations to signal price investment for the following six months, so watch commentary from Coles, Woolies and Wesfarmers for grocery, Bunnings hardware and Kmart apparel price signals.

Roy Morgan: August Retail Tipped to Hit a Record 40 Billion Dollars

Roy Morgan yesterday forecast total monthly Australian retail sales to hit 40 billion dollars for the first time ever in August 2026, up 6 per cent year on year, per Ragtrader coverage. By category, food (supermarkets) leads at 15 point 6 billion dollars (plus 4 point 6 per cent, 39 per cent of the total), other retailing including hairdressers at 7 billion (plus 5 point 7 per cent), household goods at 6 point 7 billion (plus 8 point 8 per cent, the fastest growing), hospitality at 5 point 9 billion (plus 6 point 2 per cent), fashion at 3 point 06 billion (plus 5 point 7 per cent), and department stores the slowest growing at 1 point 66 billion (plus 2 point 3 per cent).

By state Western Australia leads at plus 7 point 2 per cent to 4 point 8 billion dollars, followed by Northern Territory plus 7 point 6 per cent, South Australia plus 6 point 4 per cent, New South Wales plus 6 point 1 per cent to 12 billion, Victoria plus 5 point 9 per cent to 9 point 9 billion and Queensland plus 5 point 5 per cent to 8 point 8 billion. The bifurcation is stark: staples and household goods are compounding hard while discretionary and department stores drag, which is exactly why today s Top 5 rewards hunters who move fast on Homewares (House at 50 per cent off) and Outdoor and Camping (Macpac at 50 per cent off) before the September floor sets rotate.

Today s Top 5 Deals of the Day

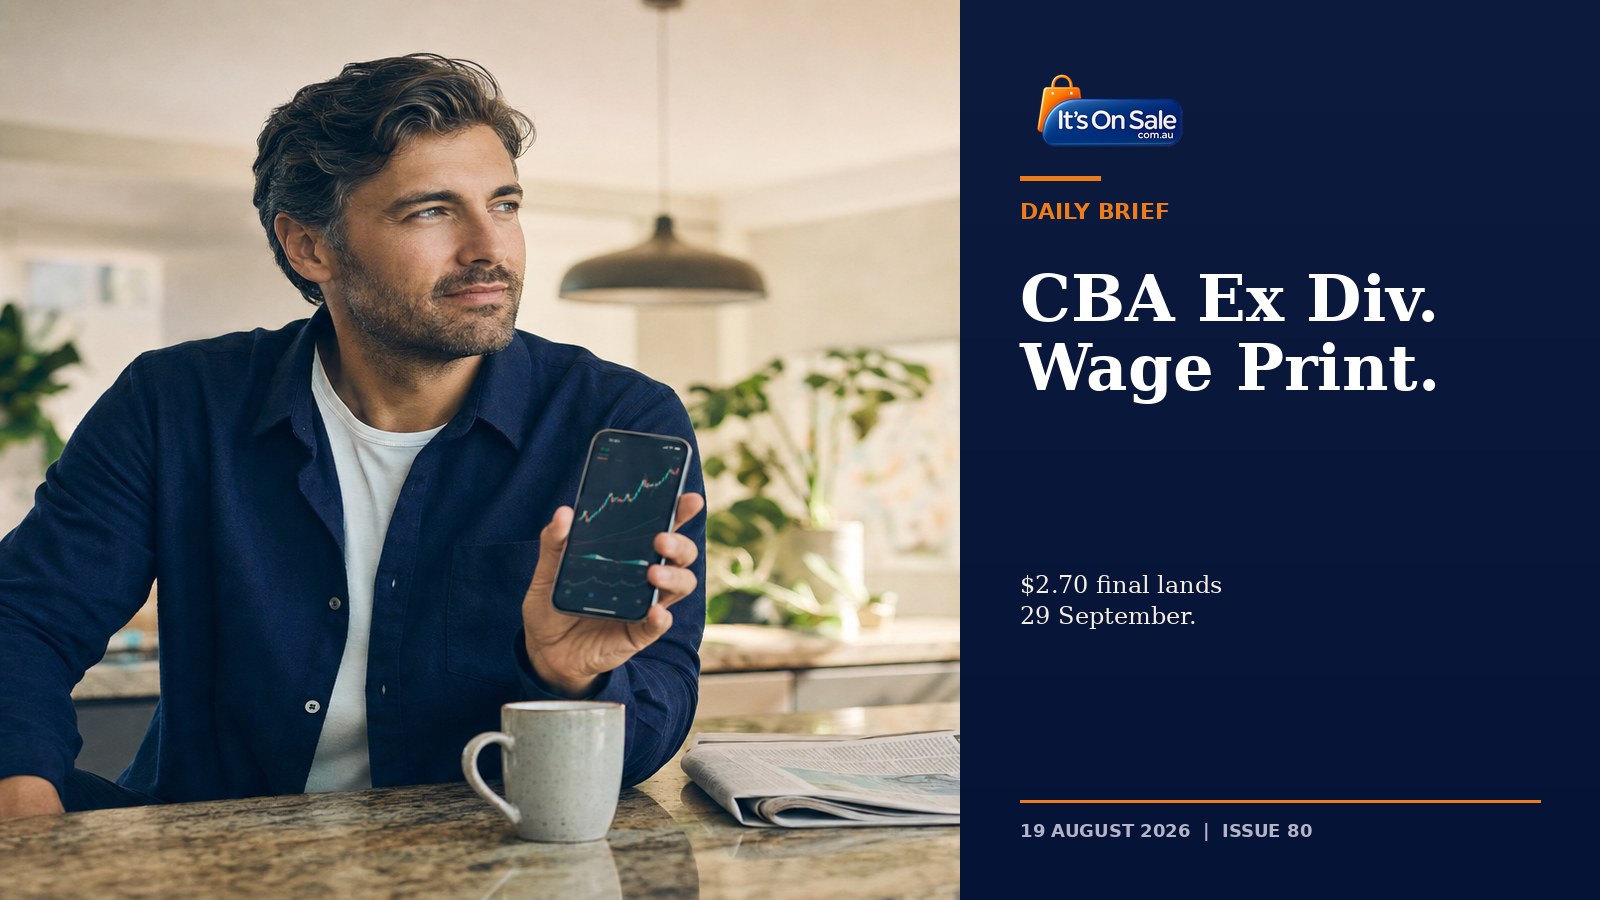
CBA Goes Ex Dividend and the June Quarter Wage Print Lands at 11:30 as BHP and CSL Reactions Roll. | It s On Sale Daily Brief, 19 August 2026

Wednesday is Wallet Wednesday for Australian households. Commonwealth Bank shares go ex dividend this morning on the 2 dollar 70 fully franked final that lands into 850 thousand retail accounts on 29 September (record date is tomorrow Thursday, DRP election closes Friday), and the ABS releases the June quarter Wage Price Index at 11:30 (the number the Reserve Bank is watching most closely before its September meeting). BHP delivered a record US 13 dollar 2 billion underlying profit yesterday and lifted the full year dividend to a four year high, while CSL surged 16 point 4 per cent on 5 per cent FY27 profit guidance despite a 2 dollar 6 billion reported loss driven by transformation impairments. Amazon remains in Federal Court on two ACCC matters. Today s Top 5 opens with Colette Hayman at 74 per cent off, then Decjuba, Myer, Robert Gordon and Australian Leather.

Wallet Wednesday: CBA Ex Div Day and the 11:30 Wage Print

Two moves land in Australian shopper wallets this morning inside a single hour. Commonwealth Bank of Australia goes ex dividend on its FY26 final dividend of 2 dollar 70 per share (fully franked) at market open (the record date is tomorrow Thursday 20 August and payment lands on Monday 29 September). CBA announced the final and total FY26 dividend of 5 dollar 05 (up 4 point 1 per cent on FY25 s 4 dollar 85) alongside the FY26 result on 12 August, with the ex, record and payment schedule confirmed in the CBA FY26 profit announcement and reiterated in the Appendix 3A.1 distribution notice. For the 850 thousand plus retail holders, that is roughly 810 dollars gross per 300 shares and 1,350 dollars per 500 shares landing in Computershare linked bank accounts in six weeks.

The second Wallet Wednesday move is the ABS Wage Price Index for the June quarter, released at 11:30am AEST. As of the March quarter release the seasonally adjusted WPI was up 0 point 8 per cent quarter on quarter and 3 point 3 per cent year on year (per the ABS March quarter release), while June quarter CPI released 30 July printed annual headline inflation at 3 point 8 per cent (per the ABS CPI June quarter media release). If today s WPI prints below 3 point 3 per cent annual, real wages continue to slip and RBA September rate cut probability sharpens, both of which typically bring retailers forward with promotion depth. A print above 3 point 4 per cent would firm the sticky wages story, and floor set discounting tends to shorten. Diarise 11:30 in your app of choice, this one flows straight into the mortgage decision.

BHP FY26: Copper Takes the Crown, Highest Dividend in Four Years

BHP Group handed down FY26 before market open yesterday Tuesday 18 August, and it was a blockbuster. Underlying attributable profit lifted 30 per cent to 13 dollar 2 billion US, comfortably above the Visible Alpha consensus of 12 dollar 66 billion US, per Reuters coverage. Revenue rose 15 per cent to 58 dollar 8 billion US, underlying EBITDA climbed 27 per cent to 32 dollar 9 billion US, and net debt fell to 8 dollar 7 billion US. The board declared a final dividend of 99 US cents per share (fully franked), taking the full year to US 1 dollar 72 (the highest annual dividend in four years) and returning 8 dollar 7 billion US to shareholders through the year. Full detail is in the BHP FY26 announcement.

The story of the year is copper: the metal accounted for 54 per cent of group underlying EBITDA (18 dollar 0 billion US) for the first time ever, overtaking iron ore. BHP produced ~2 million tonnes of copper for a second consecutive year at margins near 70 per cent, and TradingView flagged the operationally clean result plus better than expected payout drove shares up 3 per cent to 64 dollar 07 on the day. For household finances, BHP s 8 dollar 7 billion US dividend pool feeds directly into Australian superannuation balances (BHP is a top five holding across most balanced funds), and the final 99 US cent payout will settle in September into shareholder accounts on the same 850 thousand strong DRP register as CBA.

CSL FY26: Reset Year, Statutory Loss, Shares Surge 16 Per Cent on FY27 Guidance

CSL Limited reported FY26 full year results on Tuesday 18 August at 10am AEST and the headline print was ugly: statutory net loss of 2 dollar 6 billion US after 7 dollar 1 billion in impairments and restructuring costs, revenue down 1 per cent to 15 dollar 8 billion US (constant currency), and underlying NPATA of 3 dollar 1 billion US (down 2 per cent). The final dividend was maintained at US 1 dollar 62 per share, cash flow from operations held at 3 dollar 5 billion US, and CSL flagged this as a “reset year” in the CSL FY26 announcement PDF.

Investors focused entirely on the forward guidance and the market reaction was decisive. Per Investing.com coverage, CSL shares surged 16 point 4 per cent to 156 dollar 68 on the day after management guided to approximately 5 per cent underlying NPAT growth at constant currency for FY27, with CSL Behring returning to mid single digit revenue growth on strong immunoglobulin demand and new product launches. A one dollar billion buyback was completed in FY26 and CSL committed to a further 1 dollar 1 billion Australian buyback across FY27. For 240 thousand retail CSL shareholders and every Australian with a super balance, yesterday reset expectations from steady growth to transformation payoff, with the near term catalyst now the November AGM update.

Amazon Back In Court: Two Live Federal Matters

The Australian Competition and Consumer Commission has two live Federal Court proceedings against Amazon that will bear on Australian Prime subscribers and marketplace shoppers through 2026 and 2027. The first, filed in June 2026, alleges Amazon Australia included five unfair contract terms in Prime subscription contracts with more than one million annual subscribers between November 2023 and August 2025, and relied on those terms to introduce advertising to Prime Video in July 2024, requiring subscribers to pay an additional 2 dollars 99 per month to remain ad free. The case is tracked by the Australian Financial Review, with maximum penalty per contravention the highest of 50 million dollars, three times the benefit obtained, or 30 per cent of adjusted turnover during the breach period. Case management and interlocutory hearing was set for 7 August 2026.

The second proceeding, filed 29 May 2026 as NSD905 of 2026 in the Federal Court New South Wales Registry, is the first time the ACCC has taken an online marketplace to Federal Court over a mandatory product safety standard. The ACCC concise statement alleges 41 non compliant Unicorn Toddler Backpacks (containing detachable button battery light up unicorn toys without mandatory warning labels) were sold through amazon.com.au and 267 were held in Amazon s Australian fulfilment centres as of 1 November 2022. The ACCC argues that under section 136 subsection 3 of the Australian Consumer Law, mere possession or control of non compliant goods (the receiving, storing, picking, packing and shipping Amazon does for third party sellers under Fulfilment by Amazon) is enough to put the marketplace itself on the hook. If successful, this reshapes marketplace safety liability for every Fulfilment by Amazon third party seller in Australia.

Week Ahead: July Jobs Thursday, Coles Tuesday 25, Woolies Wednesday 26, Wesfarmers Thursday 28

Thursday 20 August at 11:30am AEST is the ABS July Labour Force Survey. Westpac IQ s July preview is expecting unemployment steady at 4 point 4 per cent, employment plus 15 thousand and participation at 66 point 9 per cent. Combined with today s Wage Price Index, this back to back print gives the RBA a full labour and wages picture heading into the 22 to 23 September meeting. Any soft jobs print (unemployment above 4 point 5 per cent, or employment below plus 5 thousand) would sharpen September cut expectations and typically translates within four weeks into deeper Everyday Rewards, Flybuys and MYER one targeted offers.

Next week is peak reporting for consumer facing groups. Coles Group hands down FY26 on Tuesday 25 August (media call 9:15am) with the IG earnings preview tracking consensus around 45 dollar 63 billion in sales, EBIT around 2 dollar 30 billion and final dividend per share around 43 cents (FY26 total DPS around 77 cents). Woolworths Group follows Wednesday 26 August (see the Woolworths investor page), and Wesfarmers reports Thursday 28 August with Bunnings, Kmart and Officeworks the swing divisions, per Reuters preview coverage. All three groups use FY presentations to signal price investment for the following six months, so watch commentary from Coles, Woolies and Wesfarmers for grocery, Bunnings hardware and Kmart apparel price signals.

ARC Data Backdrop: June Retail Held at 4.7 Per Cent

The Australian Retail Council s June 2026 analysis shows household retail spending at 39 dollar 68 billion in June, up 4 point 7 per cent year on year but easing from May s 5 point 8 per cent. By category, cafes, restaurants and takeaway food services grew fastest at 7 point 1 per cent, household goods retailing lifted 6 point 3 per cent, clothing plus 3 point 9 per cent, and department stores plus large online retailers were essentially flat at minus 0 point 1 per cent. The state numbers confirmed the resource state resilience: Northern Territory plus 8 point 8 per cent, Western Australia plus 7 point 5 per cent, Australian Capital Territory plus 3 point 1 per cent, New South Wales plus 3 point 2 per cent. For shoppers, the department store softness is why Myer sits at 60 per cent off in today s Top 5: mid year floor set changeover discounts this week are notably wider than a typical August.

Today s Top 5 Deals of the Day

BHP and CSL Anchor the Biggest Earnings Day of August as Consumer Sentiment Refreshes. | It s On Sale Daily Brief, 18 August 2026

Tuesday morning is the peak of ASX FY26 reporting season: BHP hands down full year before the bell with consensus underlying earnings around 32 dollar 4 billion and a final dividend around 1 dollar 56, CSL follows at 10 o clock, and Cochlear, Pro Medicus, Challenger, HUB24, Sims and Reliance Worldwide all report today. Westpac refreshes its August Consumer Sentiment index at 10:30 with the forecast a soft 81.7, and Commonwealth Bank goes ex dividend on its 2 dollar 70 final tomorrow, meaning today is the last day to buy in for the payout. Myer’s spring floor sets keep rolling. Amazon remains in Federal Court on two matters. Today’s Top 5 opens with Princess Polly at up to 80 per cent off, then Baku Swimwear, Graham s Jewellers, Telstra and General Pants Co.

Reporting Season Peak: BHP, CSL and the Health Care Nine

Tuesday 18 August 2026 is the biggest earnings day of the ASX August calendar. BHP Group reports full year FY26 before the market opens, and consensus figures compiled by Motley Fool Australia’s Tuesday preview put underlying EBITDA around 32 dollar 4 billion US, underlying NPAT around 10 dollar 8 billion US, and the final dividend around 1 dollar 56 Australian (fully franked). BHP’s July operational review already confirmed record iron ore production and its second consecutive year above 2 million tonnes of copper, so the swing factor today is how much cost inflation and China steel demand feed through into the FY27 outlook. Full guidance and payout details are in BHP s investor hub.

CSL follows at 10 o clock AEST with a briefing streamed from Melbourne. FY26 guidance set in February pointed to revenue around 15 dollar 2 billion US and NPATA around 3 dollar 1 billion, and the swing factor is Behring plasma margin recovery: analyst commentary through the run up has flagged Behring albumin and immunoglobulin pricing as the key line to watch. Cochlear reports at midday, Pro Medicus at 11, and Challenger, HUB24, Sims and Reliance Worldwide all release results today. For Australian shoppers, this cluster matters because superannuation balances shift on today s prints, and any large downgrade cluster tends to feed through into retailer promotion depth over the next three weeks as consumer confidence adjusts.

Westpac Consumer Sentiment: 10:30 AEST Release

The Westpac Melbourne Institute Consumer Sentiment Index for August lands today at 10:30am AEST. July printed at 83.9 (up 4.1 per cent month on month from June s 80.6), and the Trading Economics consensus is 81.7 for August, which would flag a modest pullback rather than a continued recovery. Any print below 82 keeps consumer sentiment in weak territory (below the neutral 100 line by more than 18 points), and any print above 85 would be the strongest reading since March 2022. The Westpac Red Book August 2026 is the same day companion piece and typically drops around 11am.

For shoppers, a soft sentiment print reinforces the cost of living squeeze narrative and validates why smart shoppers now hunt sale sections rather than shop full price. Retailers watching a soft print tend to hold discount depth through the spring reset rather than pulling promotions early: expect the current 40 to 80 per cent clearance across Princess Polly, Baku, Graham s, Telstra and General Pants to continue into next week rather than reset back to full price. A stronger than expected print would push retailers to reset floor pricing earlier and shrink the discount window, so today s number matters for anyone planning a mid week purchase.

CBA Ex Dividend Tomorrow: Last Day to Buy Today

Commonwealth Bank of Australia goes ex dividend on its FY26 final dividend of 2 dollar 70 per share (fully franked) tomorrow Wednesday 19 August 2026. Under the ASX T plus 2 settlement rule, today Tuesday is the last day investors can buy CBA shares and be on the register for the final dividend payment on 29 September. FY26 total dividends were 5 dollar 05 per share, up 4 per cent on FY25 s 4 dollar 85, and current market cap sits above 200 billion dollars. Ex dividend day typically sees the CBA share price open lower by approximately the dividend amount (2 dollar 70) all else equal, so today is also the last day for anyone considering a dividend capture trade before the reset.

For everyday shoppers not chasing dividends, CBA ex div matters because Wednesday will see the ASX 200 open lower by the CBA reset alone (roughly 15 index points on a 8000 level), and any big earnings misses today from BHP or CSL that push the miners or health care sector wider will amplify that Wednesday move. If you were planning to lock in a term deposit or transfer funds this week, the mid week Wednesday to Thursday window is when banking apps historically see the highest customer service call volumes because of ex div queries, so plan bill payments and transfers for today or Friday.

Amazon Back In Court: Two Live Federal Matters

The Australian Competition and Consumer Commission has two live Federal Court proceedings against Amazon that will bear on Australian Prime subscribers and marketplace shoppers through 2026 and 2027. The first, filed in June 2026, alleges Amazon Australia included five unfair contract terms in Prime subscription contracts with more than one million annual subscribers between November 2023 and August 2025, and relied on those terms to introduce advertising to Prime Video in July 2024, requiring subscribers to pay an additional 2 dollars 99 per month to remain ad free. The case is tracked by the Australian Financial Review, with maximum penalty per contravention the highest of 50 million dollars, three times the benefit obtained, or 30 per cent of adjusted turnover during the breach period. Case management and interlocutory hearing was set for 7 August 2026.

The second proceeding, filed 29 May 2026 as NSD905 of 2026 in the Federal Court New South Wales Registry, is the first time the ACCC has taken an online marketplace to Federal Court over a mandatory product safety standard. The ACCC concise statement alleges 41 non compliant Unicorn Toddler Backpacks (containing detachable button battery light up unicorn toys without mandatory warning labels) were sold through amazon.com.au and 267 were held in Amazon s Australian fulfilment centres as of 1 November 2022. The ACCC argues that under section 136 subsection 3 of the Australian Consumer Law, mere possession or control of non compliant goods (the receiving, storing, picking, packing and shipping Amazon does for third party sellers under Fulfilment by Amazon) is enough to put the marketplace itself on the hook. If successful, this reshapes marketplace safety liability for every Fulfilment by Amazon third party seller in Australia.

Week Ahead: July Jobs Thursday, Coles Tuesday 25, Woolies Wednesday 26

Wednesday 19 August delivers CBA ex dividend plus results from Iluka, Healius, Mirvac and Wesfarmers, plus the ABS Wage Price Index at 11:30am. Thursday 20 August at 11:30am AEST is the ABS July Labour Force Survey, and Westpac IQ s July preview is expecting unemployment steady at 4.4 per cent, employment plus 15 thousand and participation lifting to 66.9 per cent. Any soft print (unemployment above 4.5 per cent, or employment print below plus 5 thousand) would sharpen expectations of a September Reserve Bank cut, which flows directly to household mortgage headroom and discretionary retail spending.

Next week is peak grocery reporting: Coles Group hands down FY26 on Tuesday 25 August (media call 9:15am) with the IG earnings preview tracking consensus around 45 dollar 63 billion in sales, EBIT around 2 dollar 30 billion and final dividend per share around 43 cents (FY26 total DPS around 77 cents). Woolworths Group follows Wednesday 26 August, and the Woolworths investor page is the source. For shoppers, back to back grocery reports next Tuesday and Wednesday matter because both retailers use their FY presentation to signal price investment for the following six months. Any commentary flagging additional price investment tends to translate into more Everyday Rewards and Flybuys targeted offers through September and October.

ARC Data Backdrop: June Retail Held at 4.7 Per Cent

The Australian Retail Council s June 2026 analysis shows household retail spending at 39.68 billion dollars in June, up 4.7 per cent year on year but easing from May s 5.8 per cent as End of Financial Year sales delivered less real growth than the discount depth suggested. By category, cafes, restaurants and takeaway food services grew fastest at 7.1 per cent, household goods retailing lifted 6.3 per cent, clothing plus 3.9 per cent, and department stores and large online retailers were essentially flat at minus 0.1 per cent. The state numbers confirmed the resource state resilience: Northern Territory plus 8.8 per cent, Western Australia plus 7.5 per cent, Australian Capital Territory plus 3.1 per cent, New South Wales plus 3.2 per cent. For shoppers, the takeaway is that department store softness feeds through into deeper end of winter clearance today: this is why floor set changeover discounts this week are notably wider than in a typical August.

Today s Top 5 Deals of the Day

JB Hi Fi Delivers FY26 as Spring Floors Land and Reporting Week Opens. | It s On Sale Daily Brief, 17 August 2026

Monday morning delivers reporting season’s opening bell: JB Hi Fi hands down FY26 today, setting the electronics price benchmark that every other Australian retailer shadow prices against. Afterpay Day closed at 11:59pm AEST last night after four days across Myer, THE ICONIC, JB Hi Fi and JAG. Spring floor sets replaced winter overnight, and the reporting week continues with BHP FY26 Tuesday, CBA going ex dividend Wednesday and the ABS July Labour Force release Thursday. Amazon remains in Federal Court on two matters. Today’s Top 5 opens with Kickpush at up to 80 per cent off, followed by Rebel Sport, Sussan, Jac and Jack and Strandbags.

JB Hi Fi Delivers FY26: The Consumer Electronics Benchmark

JB Hi Fi Group hands down its FY26 full year result today before the market opens, and the consensus set by IG Australia’s earnings preview is a revenue print around 11.13 billion dollars (up 5.4 per cent on FY25’s 10.56 billion), net profit after tax around 493 million dollars (up 6.6 per cent) and full year earnings per share around 4 dollars 49. Full year dividends per share is expected around 3 dollars 52, down from FY25’s 3 dollars 75 because last year included a special dividend of 80 cents. Group CEO Nick Wells leads the result, and the HY26 first half was a record 6.10 billion in revenue with a 23.5 per cent interim dividend uplift.

For Australian shoppers, JB Hi Fi’s FY26 outlook matters directly: JB Hi Fi and its subsidiary The Good Guys operate the shadow price benchmark that Officeworks, Harvey Norman, Betta Home Living and Amazon Australia react to on TVs, phones, laptops, small appliances and whitegoods. If today’s guidance flags second half FY27 caution, expect wider Christmas discounting to start earlier: Black Friday windows could open in the first week of November rather than the third. If guidance is bullish, expect prices to hold firmer through spring. Analyst commentary from Roger Montgomery’s HY26 recap flagged the payout ratio lift from 65 to 70 to 80 per cent of NPAT as the key structural shift to watch through today’s result.

Afterpay Day Wrap: Four Days, One Cut Off

Afterpay Day officially ran 13 to 16 August 2026, closing at 11:59pm AEST Sunday night across every participating retailer. Historical merchant data on the Afterpay Day merchant page reports an average 24 per cent sales uplift for participating brands and 1.11 million customers per event, which explains why Myer, THE ICONIC, JB Hi Fi, The Good Guys, eBay, Petbarn, H and M and JAG all treated the four day window as a headline sale event. The Man of Many best deals wrap tracked live pricing across the run.

If you missed the window, most Afterpay Day pricing has already reverted to standard sale pricing, but not all: some retailers ladder Afterpay Day pricing into a longer end of winter clearance, meaning today and tomorrow can still show meaningful discounts on the same stock. Check Myer’s Spring Home Essentials sale running 11 to 30 August for bedding, small appliances and cookware carryover pricing, and check any Afterpay Day items you added to cart but did not check out: a small number of retailers extend the same code for an additional 24 hours through Monday. Afterpay’s four instalment split remains available on all purchases regardless of promotional status.

Spring Floor Sets Landed Overnight: What Changed Today

Overnight Sunday to Monday, Australian retailers pulled winter floor sets and rotated in spring stock. In store today: heavy coats, chunky knits, sheepskin boots, flannel sheets and doonas are moving to warehouse and online only clearance pages, and the shop floor now shows lightweight jackets, transitional knits, spring dresses, pastel tees and open toe footwear. Denim volumes lift because the shoulder season is peak denim retail: Levis, Wrangler, Jeanswest and Cotton On all reset their denim walls today.

The biggest floor set today is at Myer. Per SmartCompany reporting from 7 August, Myer is rolling out more than 25 new womenswear brands in store and online later this month, including Melbourne based Effie Kats, South Australian Acler, Significant Other, Aston Studio, Oroton’s ready to wear range, Ena Pelly, Bayse, Morrison, RAEF the Label, Byron Bay based Arcaa and Nude Lucy. International additions include British Aligne and LA activewear label Varley. If you shop Myer, expect the new arrivals to appear across the next two to three weeks alongside the existing Spring Home Essentials pricing on bedding, kitchen small appliances and cookware.

Amazon Back In Court: Two Live Matters

The Australian Competition and Consumer Commission has two live Federal Court proceedings against Amazon that will bear on Australian Prime subscribers and marketplace shoppers through 2026 and 2027. The first, filed in June 2026, alleges Amazon Australia included five unfair contract terms in Prime subscription contracts with more than one million annual subscribers between November 2023 and August 2025, and relied on those terms to introduce advertising to Prime Video in July 2024, requiring subscribers to pay an additional 2 dollars 99 per month to remain ad free. The case is tracked by the Australian Financial Review. Case management and interlocutory hearing was set for 7 August 2026. Maximum penalty per contravention is the highest of 50 million dollars, three times the benefit obtained, or 30 per cent of adjusted turnover during the breach period.

The second proceeding, filed 29 May 2026 as NSD905/2026 in the Federal Court New South Wales Registry, is the first time the ACCC has taken an online marketplace to Federal Court over a mandatory product safety standard. The ACCC concise statement alleges 41 non compliant Unicorn Toddler Backpacks (containing detachable button battery light up unicorn toys without mandatory warning labels) were sold through amazon.com.au and 267 were held in Amazon’s Australian fulfilment centres as of 1 November 2022. The ACCC argues that under section 136(3) of the Australian Consumer Law, mere possession or control of non compliant goods, that is the receiving, storing, picking, packing and shipping Amazon does for third party sellers under Fulfilment by Amazon, is enough to put the marketplace itself on the hook. If successful, this reshapes marketplace safety liability for every Fulfilment by Amazon third party seller in Australia.

Week Ahead: BHP, CBA Ex Div and the July Jobs Print

Tuesday 18 August delivers BHP FY26 with consensus around 58 dollar 3 billion revenue and 1 dollar 574 in final dividend, alongside CSL, Cochlear and Pro Medicus. Wednesday 19 August, Commonwealth Bank goes ex dividend on its 2 dollar 70 fully franked final dividend (FY26 total 5 dollar 05, up 4 per cent on FY25’s 4 dollar 85, paid 29 September 2026): if you own CBA and want the dividend, hold at Tuesday’s close. Thursday 20 August at 11:30am AEST is the ABS July Labour Force Survey. Westpac IQ’s July preview is expecting unemployment steady at 4.4 per cent, employment plus 15 thousand and participation lifting to 66.9 per cent. Full reporting calendar is at the Motley Fool Australia reporting season page.

For consumer facing retail, the mid week gap between BHP Tuesday and CBA ex div Wednesday is historically when retailers push discounting to counter market softness. If you are planning larger purchases such as appliances, whitegoods or furniture, watching for Wednesday flash promotions can capture retailer reactions to any soft results. The ABS July jobs print on Thursday will also influence Reserve Bank pricing expectations ahead of the September rate decision.

ARC Data Backdrop: June Retail Held at 4.7 Per Cent

The Australian Retail Council’s June 2026 analysis shows household retail spending at 39.68 billion dollars in June, up 4.7 per cent year on year but easing from May’s 5.8 per cent as End of Financial Year sales delivered less real growth than the discount depth suggested. By category, cafes, restaurants and takeaway food services grew fastest at 7.1 per cent, household goods retailing lifted 6.3 per cent, clothing plus 3.9 per cent, and department stores and large online retailers were essentially flat at minus 0.1 per cent. The state numbers confirmed the resource state resilience: Northern Territory plus 8.8 per cent, Western Australia plus 7.5 per cent, Australian Capital Territory plus 3.1 per cent, New South Wales plus 3.2 per cent. For shoppers, the takeaway is that department store softness feeds through into deeper end of winter clearance today: this is why floor set changeover discounts this week are notably wider than in a typical August.

Today’s Top 5 Deals of the Day

Afterpay Day ends tonight, last winter Sunday before spring floors

Afterpay Day Ends Tonight, Last Winter Sunday Before Spring Floors Land Monday. | It s On Sale Daily Brief, 16 August 2026

Sunday and today is the final day of Afterpay Day, closing at 11:59pm AEST tonight across Myer, THE ICONIC, JB Hi Fi, The Good Guys, eBay, Petbarn, H and M and JAG. It is also the last winter clearance Sunday before spring floor sets land Monday 18 August. The week ahead delivers reporting season’s biggest cluster: JB Hi Fi FY26 result Monday, BHP FY26 Tuesday, ABS July Labour Force Wednesday morning, CBA going ex dividend Wednesday. Amazon is back in Federal Court over Prime Video ads, and the ARA has flagged GFC scale discounting from a warm winter overhang. Today’s Top 5 opens with Cotton On Clothing at up to 50 per cent off, followed by Kathmandu, Portmans, Typo and Lounge Lovers.

Afterpay Day Ends Tonight: The 11:59pm AEST Cut Off

Afterpay Day officially runs 13 to 16 August 2026, and every participating retailer switches their sale pages back to regular pricing at 11:59pm Australian Eastern Standard Time tonight. The biggest confirmed offers across the four day run include Myer with up to 60 per cent off flash deals, THE ICONIC with tiered fashion discounts, JB Hi Fi and The Good Guys with electronics bundles, eBay with sitewide promotional codes, Petbarn with up to 40 per cent off pet essentials, H and M with 20 per cent off almost everything and JAG with 20 per cent off full price plus 30 per cent off two or more items. Hush Puppies is offering 25 per cent off sitewide as one of its participating brands. Reference the Afterpay Day 2026 lineup on 7You reporter Fashion desk coverage at 7NEWS.

Sunday tactical actions for Australian shopper households. First, confirm the promotional code where required: Myer, THE ICONIC and eBay use different sale pages depending on category, and a handful of brands require the checkout code (H and M, JAG) versus automatic pricing. Second, use Afterpay’s four instalment split on higher ticket items you were already going to purchase, such as a JB Hi Fi appliance or a Good Guys bundle: the same four fortnight split is available on any Afterpay Day purchase and no promotional code is required for Afterpay itself. Third, if you were undecided between two size or colour choices, order both today with the intent to return one within the seven to fourteen day window: most participating retailers extend free returns during Afterpay Day. Fourth, avoid stacking with third party cashback platforms unless the platform explicitly confirms Afterpay Day works in stack: some retailers exclude promotional windows. Fifth, remember the 11:59pm AEST deadline is Eastern Standard Time not local time: Perth shoppers have until 9:59pm local, Adelaide shoppers until 11:29pm local. TopCashback flagged one day flash offers for the final day per Medianet retail news.

Last Winter Sunday: Spring Floor Sets Land Monday

Monday 18 August triggers the transition. In store, retailers pull remaining winter stock overnight Sunday to Monday: heavy coats, chunky knits, sheepskin boots, flannel sheets and doonas move to warehouse or online only clearance pages, and the shop floor is repurposed with lightweight jackets, transitional knits, spring dresses, pastel tees and open toe footwear. The two Sundays before the switch typically see the deepest discounts on winter stock, but by Sunday afternoon size ranges have thinned significantly. Myer’s Spring Home Essentials sale is already running 11 to 30 August and includes bedding, small appliances and cookware discounts that ladder into the post transition weeks.

Practical Sunday moves: if you saw a coat at 40 per cent off last weekend and hesitated, check its current price today because it is likely 60 to 70 per cent off by now. Buy 12 months ahead on kids’ winter school jackets and adult heavy coats since Australian retailers do not repeat this discount depth until July 2027. Combine winter picks with a spring transition piece from the same retailer to hit free shipping thresholds (typically 100 dollars) and avoid the courier surcharge. Keep receipts and tags on for exchange window flexibility. The Australian Retailers Association’s Russell Zimmerman told 9News this month that warm winter weather has driven GFC like discounting: consumer benefit today, but a signal that clearance depths this weekend are unusually generous.

Week Ahead: Reporting Season Cluster and CBA Going Ex Dividend

Monday 17 August delivers JB Hi Fi FY26 full year result. Consensus per IG Australia sits at around 11.1 billion dollars revenue and 3.566 dollars in full year dividends per share, with the market watching whether the record HY26 first half of 6.10 billion (up 7.3 per cent) is sustained through a softer second half. Tuesday 18 August sees BHP report FY26 with consensus around 58.3 billion dollars revenue and 1.574 dollars in dividends per share (final component), alongside CSL, Cochlear and Pro Medicus. Wednesday 19 August is the ABS July Labour Force Survey at 11:30am AEST, previous print was 4.4 per cent unemployment (unchanged). Same day, Commonwealth Bank goes ex dividend on its 2 dollar 70 fully franked final dividend (paid 29 September 2026): if you own CBA and want the dividend, you need to hold at Tuesday’s close. If you are considering buying CBA post dividend, the share price typically drops by roughly the dividend amount on Wednesday morning. Full reporting calendar is available on the Motley Fool Australia and Lincoln Indicators reporting season pages.

Amazon Back In Court: ACCC v Amazon Commercial Services

The Australian Competition and Consumer Commission commenced Federal Court proceedings against Amazon Commercial Services in June 2026, alleging Amazon introduced advertising into Prime Video for existing Australian subscribers using unfair contract terms without adequate consent. This is the first contested matter under the new unfair contract terms penalty regime introduced in November 2023, and the ACCC is seeking pecuniary penalties, declarations and consumer redress. For Australian Prime subscribers, this means potential refunds or ad free reinstatement if the ACCC succeeds. The case underscores the ongoing regulatory push against dominant marketplace operators. Full case detail is on the ACCC’s media release page.

Sunday Recap: Australian Retail Context

The Australian retail sector is entering its final winter weekend with unusual clearance depth driven by a warmer than average winter and heightened discretionary spend caution. Consumer confidence remains subdued despite recent RBA cash rate cuts, and reporting season this week will provide the first cross sector read on retail margins for FY26 second half. JB Hi Fi’s Monday result is the bellwether for consumer electronics and appliances; Bank of Queensland, Insignia Financial and Nine Entertainment through the week will paint the picture for financial services, media and platform economics. If you are planning larger purchases such as appliances, whitegoods or furniture, timing them into the mid week gap between reporting announcements can capture retailer promotional activity as they push back against soft results with consumer facing offers.

Today’s Top 5 Deals of the Day

Final Winter Clearance Weekend, CBA Ex Div Wednesday, JB Hi Fi and BHP Results Ahead. | It s On Sale Daily Brief, 15 August 2026

Saturday, and this is the final full-choice weekend to grab winter stock before spring floor sets land Monday 18 August. Reporting season peaks in the week ahead: JB Hi Fi FY26 Monday, BHP FY26 Tuesday, ABS July Labour Force Survey Wednesday morning, CBA final dividend goes ex on Wednesday. Zara Australia profit slid 25 per cent in the latest annual filing per Ragtrader. Amazon extended same day delivery to Adelaide, squeezing weekend fulfilment margins for local retailers. Today’s Top 5 opens with Kick Push Skate at up to 80 per cent off skate hardware, followed by Betts at up to 70 per cent off footwear and Sportsgirl at up to 70 per cent off womens fashion.

Final Winter Clearance Weekend: Two Days To Buy the Coat

Saturday 15 August and Sunday 16 August are the final two full-choice days for winter stock at major Australian fashion, footwear and homewares retailers. From Monday 18 August, spring floor sets land in stores and remaining winter stock is pulled to warehouse or online-only clearance pages. Practically this means: the coat rack you saw last week at 40 per cent off is at 60 per cent off today and 70 to 80 per cent off by Sunday afternoon, but the size and colour choice narrows every hour. By Monday morning, the wall becomes lightweight jackets, transitional knits, spring dresses and pastel tees. This weekend is when the year’s deepest sale prices on winter woollens, sheepskin boots, heavy denim, thermals, doonas and throws converge with the last of the pre-transition size range.

Weekend tactical actions for Australian shopper households. First, prioritise categories that get pulled Monday: heavy coats, chunky knits, sheepskin boots, thermals, flannel sheets, winter doonas. Second, size up before you size down. If your usual size is a Medium, check Large first because the popular sizes go first at the deepest discounts. Third, buy 12 months ahead for kids’ winter uniforms and school jackets. Australian retailers rarely repeat the same discount depth on winter stock until the following July clearance. Fourth, keep receipts and tags on: most stores extend change of mind exchanges through the transition period, but each has its own window. Fifth, if the store lists free Australia wide shipping over a threshold (Betts from 100 dollars, Sportsgirl from 100 dollars, most others from 100 to 150 dollars), combine winter picks with a spring transition piece to hit free freight and avoid the courier fee.

Week Ahead: FY26 Reporting Season Peaks

Four dates matter for Australian shopper wallets across the coming week. JB Hi Fi reports FY26 Monday 17 August, market watching for underlying sales growth in the June quarter and any commentary on the pace of Q1 FY27 trading through August. BHP reports FY26 Tuesday 18 August, with the final dividend and iron ore realisation the two consumer-adjacent watchpoints (superannuation exposure sits in the AUD franking pool). Wednesday 19 August is a double header: the ABS releases the July Labour Force Survey at 11:30am AEST with Trading Economics forecasting unemployment at 4 point 5 per cent up from June’s 4 point 4 per cent, and CBA shares go ex-dividend for the FY26 final of 2 dollars 70 cents per share fully franked. Thursday 20 August adds Brambles and Goodman Group, both indirectly relevant to warehouse rents and last-mile logistics costs that flow through to retail pricing.

For household budgets the July jobs print is the single most consequential release of the week. If unemployment prints at 4 point 5 per cent as Trading Economics forecasts, weakening jobs momentum pushes RBA November hike odds materially lower and gives 3 point 3 million mortgaged households a clearer glide path into Christmas. If July prints BELOW 4 point 4 per cent with continued strong employment growth, the RBA’s hawkish August rhetoric converts into a real November move and household budgets tighten. Watch three sub-numbers alongside the headline: participation rate (record highs signal hidden strength), hours worked (softening signals hiring restraint), and underemployment (June’s 6 point 5 per cent was the highest since August 2024). All three together tell the fuller story.

CBA Ex-Div Wednesday: 2 Dollars 70 Cents Fully Franked

Commonwealth Bank of Australia (ASX: CBA) declared a final dividend of 2 dollars 70 cents per share fully franked with the FY26 result on 12 August, taking the full year total to 5 dollars 05 cents fully franked, up 5 cents on FY25. Shares closed Thursday 13 August at 169 dollars 00 cents, down 2 point 15 per cent on the day per Motley Fool coverage of next week’s ex-div calendar. Ex-dividend date is Wednesday 19 August, record date Thursday 20 August, DRP election deadline Thursday 21 August, and payment date Monday 29 September 2026. For the 850,000 CBA retail shareholders, that is 810 dollars gross per 300 shares held on 18 August, or 1,350 dollars per 500 shares.

Practical shopper takeaway. If you hold CBA shares in your own name or through a super fund, the 29 September payment lands into the account you have registered with Computershare. If you have moved bank accounts in the last 12 months, log into Computershare Investor Centre before Wednesday 19 August and confirm the account details on file. If you are enrolled in the Dividend Reinvestment Plan (DRP), the FY26 final DRP shares will be issued at a small discount to the volume weighted average price over the pricing period, giving a modest reinvestment tailwind. The DRP election deadline is Thursday 21 August. Straight cash into the everyday account for the September school and utility bills, or DRP for the small compounding kicker: your call, but the decision window closes Thursday.

Amazon Same Day Rolls Into Adelaide, Squeezing Local Retail

Amazon Australia extended its same day delivery service to Adelaide postcodes this week, per multiple retail trade outlets covering the announcement. That takes same day coverage to five capital cities (Sydney, Melbourne, Brisbane, Perth, Adelaide) with Hobart, Darwin and Canberra still on next day. For Australian shoppers on Prime the practical shift is that a Saturday morning order placed by 10am now lands the same afternoon in metro Adelaide, matching the Amazon logistics footprint of the US Prime Now service that gutted mall foot traffic in mid-tier US cities across 2016 to 2022.

The squeeze on local retail is real. Australian owned specialty stores selling homewares, small electronics, toys, books and pantry staples now face a same day fulfilment benchmark on 60 per cent of the AU population without matching the Amazon fixed cost base. Independent retailers that have not moved to click and collect or a local courier partnership are already reporting weekend basket size drops of 10 to 15 per cent in categories where Amazon is size-competitive. The consumer counter-move is not to boycott Amazon (it is now a fact of the AU retail floor) but to remember three things this weekend. First, the Australian Consumer Law applies to every Amazon AU order, but recourse is materially slower on marketplace listings shipped from overseas than on locally owned retailers. Second, on price parity, buying from an Australian owned store keeps the margin in the AU tax and wage base. Third, Amazon does not carry the depth of size range in fashion or footwear that a specialist like Betts, Sportsgirl or Kick Push Skate does, and that is exactly where the deepest weekend discounts sit.

Zara Australia Profit Slips 25 Per Cent

Inditex-owned Zara Australia reported a 25 per cent decline in annual profit in the latest local filing, per Ragtrader coverage of the Australian retail industry this week. Revenue growth slowed and margin compression from freight, wages and store rent hit the local P and L harder than analysts expected. The result is another datapoint in a global fast-fashion softening story that includes softer H and M AU comparable store sales, Peter Alexander shutting all remaining UK stores per The West Australian retail desk, and Uniqlo pausing new AU store openings for the second half of the year.

The shopper read across is straightforward. When international fast fashion softens in AU, the vacuum gets filled by Australian owned specialty and mid-market retailers running deep clearance to protect market share. This weekend, that means the Sportsgirl 70 per cent off run and the Betts 70 per cent off footwear window are more competitive on price and range than the equivalent Zara or H and M clearance rack, and the after-sale service (returns, exchanges, alterations at Betts) is materially better. Every store in today’s Top 5 is Australian owned or locally fulfilled. Every discount was verified against the store’s own live sale page this morning.

Saturday Top 5 Deals

Every store in Saturday’s Top 5 is Australian owned or locally fulfilled. Every discount was verified against the store’s own live sale page this morning. None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Every product ships from an Australian warehouse and is backed by the Australian Consumer Law. Kick Push Skate leads today at up to 80 per cent off complete skateboards, decks, trucks, wheels, bearings, safety gear, scooters and skate shoes from the Australian owned skate specialist since 2003. Betts follows at up to 70 per cent off heels, flats, boots, loafers, sneakers and handbags from the Australian footwear retailer since 1892. Sportsgirl at up to 70 per cent off delivers dresses, tops, denim, coats and knits from the iconic Australian womens fashion retailer since 1948. OPSM at up to 50 per cent off runs across designer prescription sunglasses, optical frames and contact lens packs. Scooter Hut at up to 50 per cent off closes the Top 5 with stunt scooters, complete scooters, decks, forks, wheels and safety gear from the Australian owned scooter specialist since 2007.

Other Deals Worth A Look

Beyond the Top 5, a handful of other Australian owned or locally fulfilled retailers are worth a Saturday scroll. Sunnylife (today’s Top 6 ticker pick) holds up to 50 per cent off summer swim, pool floats, beach umbrellas, coolers and outdoor lifestyle homewares from the Sydney founded lifestyle label ahead of the spring transition. Barney Cools at 38 per cent off runs tees, shorts, boardies and lightweight jackets ahead of the summer season. Veronika Maine at 30 per cent off holds tailoring, dresses and coats from the Sydney founded contemporary womens label. All Australian owned or locally fulfilled, all backed by the Australian Consumer Law.

Our Take

Saturday 15 August is the final full-choice day for winter stock at Australian retailers before spring floor sets land Monday. From Monday morning the coat wall is replaced by lightweight jackets and pastel tees. If a winter jacket, boots, thermals or a heavier knit is still on the wardrobe list, this weekend is the deadline. Reporting season peaks next week with JB Hi Fi FY26 Monday, BHP FY26 Tuesday, ABS July jobs and CBA ex-div Wednesday. The jobs print is the single most important data point for the RBA’s November decision. Amazon same day now covers 60 per cent of the AU population, and the counter-move for shoppers is to remember that Australian owned specialty retailers still carry the deepest size range and the best after-sale service. Zara Australia’s 25 per cent profit slip is another datapoint in a broader global fast-fashion softening story that opens room for Australian owned mid-market retailers to hold market share with weekend clearance depth.

That is exactly why It’s On Sale exists. We track 35,000 Australian stores and 45,000 live sale products, every retailer Australian owned or locally fulfilled, every promotion audited daily against the store’s own price history. No trial traps, no hidden fees, no offshore marketplaces dressed up as a local brand. Today’s Sales shows every store currently running a discount in one place. The AI search reads the way real shoppers ask (try “winter coat clearance” or “kids scooter sale”). None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Browse Today’s Sales this Saturday morning to hit the final winter clearance weekend at Australian retailers who stand behind the ticket and the Australian Consumer Law.

It's On Sale Daily Brief Issue 75 hero image

July Jobs Print Today at 1130am, Telstra FY26 Wrap, Last Winter Clearance Weekend. | It s On Sale Daily Brief, 14 August 2026

Friday, and the number that sets the RBA tone for the rest of August drops at 11:30am AEST. The ABS releases the July Labour Force Survey this morning with Trading Economics forecasting unemployment at 4 point 5 per cent, up from June’s 4 point 4 per cent, alongside participation at a 12 month high of 67 point 0 per cent and 76,300 extra jobs added the month prior. Yesterday Telstra Group FY26 delivered underlying EBITDAaL of 8 point 3 billion dollars near the top of guidance, a full year dividend of 21 cents per share up 10 point 5 per cent, and a fresh 1 billion dollar share buyback, yet shares still slid 5 point 2 per cent intraday to 4 dollars 74 cents on softer FY27 revenue signals and postpaid subscriber pressure. This is the final winter clearance weekend at Australian retailers, with spring floor sets landing Monday 18 August. Today’s Top 5 opens with Dusk at up to 80 per cent off candles and home fragrance, followed by Showpo at up to 80 per cent off womens fashion and UGG Express at up to 80 per cent off sheepskin boots.

July Jobs Print Today at 11:30am AEST

The Australian Bureau of Statistics releases the July Labour Force Survey this morning at 11:30am AEST, per the ABS Labour Force calendar. June printed at 4 point 4 per cent unemployment (unrounded 4 point 35 per cent) with 76,300 more people in work month on month, the largest monthly employment gain since April last year per Reuters coverage of the June release. Participation lifted to a one year high of 67 point 0 per cent. Trading Economics forecasts July at 4 point 5 per cent, up 0 point 1 percentage point.

The consequence chain for Australian shopper households runs through interest rates. On Tuesday the RBA held the cash rate at 4 point 35 per cent but Governor Bullock struck a hawkish tone, warning it was quite possible the RBA might need to go and that interest rates might need to stay high for longer. Swap markets now price a real chance of a November hike. If July prints AT OR ABOVE 4 point 5 per cent, weakening jobs momentum removes wage inflation pressure and pushes November hike odds materially lower, giving 3 point 3 million mortgaged households a clearer glide path. If July prints BELOW 4 point 4 per cent with continued strong employment growth, the RBA’s hawkish stance converts into a real November move and household budgets tighten into Christmas. Watch three sub-numbers alongside the headline: participation rate (record highs signal hidden strength), hours worked (softening signals hiring restraint), and underemployment (June’s 6 point 5 per cent was the highest since August 2024). All three together tell the fuller story.

Telstra FY26 Aftermath: Buyback Rewarded, Share Price Punished

Yesterday Telstra Group landed FY26 with underlying EBITDAaL of 8 point 3 billion dollars, up 4 per cent and near the top of the 8 point 2 to 8 point 4 billion dollar guidance range, per Market Index coverage. Reported net profit after tax was 2 point 4 billion dollars, up 2 point 7 per cent, and cash earnings per share climbed 14 per cent to 25 point 5 cents. The board declared a final dividend of 10 point 5 cents per share 90 point 5 per cent franked, taking the FY26 total to 21 cents per share, up 10 point 5 per cent year on year. On top of that, Telstra announced a fresh 1 billion dollar on-market share buyback. Despite the shareholder friendly announcements, per The Motley Fool Australia, shares opened at 4 dollars 95 cents, hit an intraday low of 4 dollars 74 cents (down 5 point 2 per cent), and closed at 4 dollars 82 cents, down 3 point 2 per cent on the day.

What went wrong for the share price. Group revenue slipped 0 point 8 per cent to 22 point 9 billion dollars, per Rask Media’s FY26 breakdown. Fixed enterprise EBITDA fell 16 point 7 per cent as data and connectivity margins compressed. Investors also weighed subscriber pressure in branded postpaid mobile following the July 2025 price hikes, the lingering impact of the July 2024 network outage that cost CEO Vicki Brady 607,000 dollars of her bonus per IG’s afternoon market report, and elevated capital spending requirements. FY27 EBITDAaL guidance of 8 point 5 to 8 point 8 billion dollars implies only 1 point 9 to 5 point 5 per cent growth, softer than the market wanted. Approximately 1 point 5 million Telstra retail shareholders now have a diary date: Telstra ex-dividend date is Tuesday 26 August 2026, 12 days from today. Record date is Wednesday 27 August. Payment date is Thursday 24 September, per The Motley Fool’s dividend explainer. For Telstra mobile customers the practical takeaway is that FY27 revenue guidance implies continued postpaid ARPU discipline but no headline price rise cliff, and now is a good weekend to check if a competitor plan on the same tower undercuts your current bill by 10 dollars or more per month.

Last Winter Clearance Weekend: Two Days To Buy the Coat

Today, tomorrow Saturday 15 August and Sunday 16 August are the final three full-choice days for winter stock at major Australian fashion, footwear and homewares retailers. From Monday 18 August, spring floor sets land in stores and remaining winter stock is pulled to warehouse or online-only clearance pages. Practically this means: the coat rack you saw last week at 40 per cent off is at 60 per cent off today and 70 to 80 per cent off by Sunday afternoon, but the size and colour choice narrows every hour. By Monday morning, the wall becomes lightweight jackets, transitional knits, spring dresses and pastel tees. This weekend is when the year’s deepest sale prices on winter woollens, sheepskin boots, heavy denim, thermals, doonas and throws converge with the last of the pre-transition size range.

Weekend tactical actions for Australian shopper households. First, prioritise categories that get pulled Monday: heavy coats, chunky knits, sheepskin boots, thermals, flannel sheets, winter doonas. Second, size up before you size down. If your usual size is a Medium, check Large first because the popular sizes go first at the deepest discounts. Third, buy 12 months ahead for kids’ winter uniforms and school jackets. Australian retailers rarely repeat the same discount depth on winter stock until the following July clearance. Fourth, keep receipts and tags on: most stores extend change of mind exchanges through the transition period, but each has its own window. Fifth, if the store lists free Australia wide shipping over a threshold (Dusk from 89 dollars, Showpo from 50 dollars, UGG Express from 100 dollars, Merchant 1948 from 150 dollars, most others from 100 to 150 dollars), combine winter picks with a spring transition piece to hit free freight and avoid the courier fee.

Fuel Day 12: Peak Likely Past

Today is Day 12 of full fuel excise restoration. Petroleum tax jumped from 20 point 6 cents per litre in April to June, to 36 point 6 cents per litre between 1 July and 2 August (partial), to the full 53 point 7 cents per litre from 3 August, per the Australian Taxation Office. The ACCC 22nd weekly fuel price monitoring report to 5 August showed 5-city retail petrol at 207 point 5 cents per litre and diesel at 246 cents per litre. The ACCC 23rd weekly report is expected today and will confirm whether the retail petrol cycle peaked earlier this week, per FuelPlan.gov.au. Retail petrol should now be trending gently down through the weekend as service stations shed the peak day margin.

Friday weekend tactical actions for Australian drivers. First, before you leave the driveway check Fuel Check NSW, FuelWatch WA, FuelCheck TAS, MyFuel NT, MotorMouth or PetrolSpy. Metro cheapest to most expensive gaps remain wide at 40 to 60 cents per litre through weekend cycles. Second, if your vehicle handbook allows a grade drop from Premium 98 to U91 or E10, NRMA data has the grade spread at a record 26 point 5 cents per litre. On a 55-litre fill that is 14 dollars 60 cents saved per tank. Third, delay a full tank until Sunday or early Monday. If the retail cycle peaked Wednesday or Thursday, Sunday afternoon should be 5 to 8 cents per litre below Friday morning at the same station. On 55 litres that is 3 to 4 dollars per fill.

Friday Top 5 Deals

Every store in Friday’s Top 5 is Australian owned or locally fulfilled. Every discount was verified against the store’s own live sale page this morning. None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Every product ships from an Australian warehouse and is backed by the Australian Consumer Law. Dusk leads today at up to 80 per cent off scented candles, diffusers, home fragrance, wax melts and lanterns from the Australian owned home fragrance retailer since 2000 with more than 130 stores across the country. Showpo follows at up to 80 per cent off dresses, tops, denim, coats and knits from the Sydney founded Australian womens fashion retailer since 2010. UGG Express at up to 80 per cent off delivers classic and mini UGG boots, tall boots, slippers, moccasins and kids and mens sheepskin footwear. Nine West at up to 60 per cent off runs across heels, flats, ankle boots, sneakers, sandals and handbags. Eckersleys at up to 50 per cent off closes the Top 5 with art supplies, canvases, paints, brushes, papers, sketchbooks and craft materials from the Australian owned art and craft specialist since 1892.

Other Deals Worth A Look

Beyond the Top 5, a handful of other Australian owned or locally fulfilled retailers are worth a Friday scroll. P.E Nation (today’s Top 6 ticker pick) holds 30 per cent off across technical activewear, hoodies, joggers, tees and matching sets from the Sydney founded contemporary activewear label. UGG continues at 30 per cent off classic sheepskin boots and slippers. Veronika Maine holds 30 per cent off tailoring, dresses and coats from the Sydney founded contemporary womens label. All Australian owned or locally fulfilled, all backed by the Australian Consumer Law.

Week Ahead

Three dates matter for Australian shopper wallets across the coming week. Today Friday 14 August 11:30am AEST: ABS July Labour Force Survey release, Trading Economics forecast 4 point 5 per cent unemployment up 0 point 1 percentage point. Saturday 15 August and Sunday 16 August: final winter clearance weekend at Australian fashion, footwear and homewares retailers, spring floor sets land Monday 18 August. Tuesday 26 August: Telstra ex-dividend date, 10 point 5 cents fully franked (90 point 5 per cent franked) final dividend paid 24 September. Thursday 21 August: CBA DRP election deadline for the 5 dollars 5 cents fully franked dividend that pays 29 September.

Our Take

Friday 14 August is the day the ABS releases the single most important data point for the RBA’s November decision. If unemployment prints at 4 point 5 per cent as Trading Economics forecasts, mortgage relief moves closer and household discretionary spending gets a slow tailwind into Christmas. If it prints lower with continued strong employment growth, hawkish RBA rhetoric converts into a real fourth rate rise this year. Yesterday Telstra rewarded shareholders with a 21 cent full year dividend and a 1 billion dollar buyback, but shares still fell 5 per cent on softer FY27 revenue guidance. This is the FINAL WEEKEND for winter clearance at Australian retailers. From Monday 18 August, spring floor sets replace winter stock and today’s headline discounts on remaining coats, knits, boots, thermals and doonas are the deepest and last full-choice window of the year. If a winter jacket, boots, thermals or a heavier knit is still on the wardrobe list, this weekend is the deadline.

That is exactly why It’s On Sale exists. We track 35,000 Australian stores and 45,000 live sale products, every retailer Australian owned or locally fulfilled, every promotion audited daily against the store’s own price history. No trial traps, no hidden fees, no offshore marketplaces dressed up as a local brand. Today’s Sales shows every store currently running a discount in one place. The AI search reads the way real shoppers ask (try “winter coat clearance” or “candles on sale”). None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Browse Today’s Sales this Friday morning to hit the final winter clearance weekend at Australian retailers who stand behind the ticket and the Australian Consumer Law.

Editorial hero, Telstra FY26 and July unemployment preview

Telstra FY26 at 9:15am, Jobs Data Tomorrow, CBA Ex-Div in 6 Days. | It s On Sale Daily Brief, 13 August 2026

Thursday, and the reporting season baton passes from bank to telco. Telstra Group releases its FY26 full year result at 9:15am AEST this morning: FY26 EBITDAaL guidance sits at 8 point 2 to 8 point 4 billion dollars, cash EBIT guidance at 4 point 55 to 4 point 75 billion dollars, and the market is watching for a buyback extension after the 1 billion dollars announced last August. Yesterday CommBank landed cash NPAT of 11 billion dollars, up 7 per cent, and declared a full year dividend of 5 dollars 5 cents fully franked, up 4 per cent, but shares still fell 0 point 6 per cent to 172 dollars 87 cents at 28 times price to earnings, and ex dividend is Tuesday 19 August, just six days away. Tomorrow Friday 14 August at 11:30am AEST the ABS drops the July Labour Force Survey with Trading Economics forecasting unemployment at 4 point 5 per cent, up from June’s 4 point 4 per cent. Fuel Day 11 today, retail petrol cycle at or through peak on 5 city average of 207 point 5 cents per litre and diesel 246 cents per litre, with the ACCC 23rd weekly monitoring report due today or tomorrow. Today is the final full winter clearance day at major retailers before spring floor sets tomorrow Friday 15 August. Today’s Top 5 opens with Mossman at up to 70 per cent off womens contemporary fashion from the Melbourne based label, followed by Hallensteins at up to 50 per cent off mens tees, hoodies, denim and knits.

Telstra FY26 Result Landing at 9:15am AEST

Telstra Group releases its FY26 full year result to the ASX at 9:15am AEST this morning, per the Telstra investor relations page. The 1H26 half year result already banked FY26 revenue excluding financing of 11 billion 641 million dollars, underlying EBITDAaL of 4 billion 185 million dollars, and a 1H26 interim dividend of 10 point 5 cents per share 90 point 5 per cent franked, per GO Markets FY26 result preview. Full year EBITDAaL guidance sits at 8 point 2 to 8 point 4 billion dollars and cash EBIT guidance at 4 billion 550 to 4 billion 750 million dollars. Intelligent Investor’s FY26 forecast per their TLS page is NPAT 2 billion 415 million dollars, EPS 20 point 90 cents, and DPS 19 cents fully franked, a 4 per cent lift on FY25.

What Australian shopper households should watch beyond the headline dividend. First, postpaid mobile ARPU direction: 1H26 postpaid ARPU printed at 56 dollars 22 cents, up 4 point 8 per cent year on year on the back of the July 2025 CPI-linked mobile price rise, and FY26 FY guidance will confirm whether Telstra models a CPI-plus price rise for FY27 too. Second, buyback extension size: last August Telstra announced a 1 billion dollar buyback for FY26 on top of February’s 750 million dollar tranche, and any FY27 buyback announcement lifts the 1 point 5 million retail shareholder dividend yield. Third, NBN reseller margins and enterprise softness. Fourth, InfraCo Fixed Line separation update timeline. For Australian mobile customers the practical takeaway is that Telstra is likely to guide for another mid single digit ARPU lift in FY27, meaning postpaid plans continue to migrate upward.

CommBank FY26 Aftermath: Shares Down, Dividend Locked, Ex Div Next Tuesday

Yesterday Commonwealth Bank of Australia landed its FY26 full year result at 9:30am AEST with a full year cash NPAT of 11 billion dollars, up 7 per cent, statutory NPAT of 10 billion 910 million dollars, up 8 per cent, and a full year dividend of 5 dollars 5 cents per share fully franked (final dividend 2 dollars 70 cents on top of the 2 dollars 35 cents interim), per the CBA FY26 ASX announcement. Sebastian Bowen at The Motley Fool Australia on 12 August reported shares closed at 172 dollars 87 cents, down 0 point 6 per cent on the day, at a forward price to earnings ratio of 28 times, roughly in line with the ASX 200’s 0 point 5 per cent close at 9,209.

Approximately 800,000 CBA retail shareholders, most of them Australian household savers who own the stock directly or through their SMSF, have three key dates on the calendar. Ex dividend date is Tuesday 19 August 2026, just six days from today. Record date is Wednesday 20 August. DRP election deadline is Thursday 21 August. Payment date is Monday 29 September. That 5 dollars 5 cents fully franked pays out to approximately 800,000 Australian retail investors on 29 September, an injection of over 4 billion dollars into household spending accounts in the September quarter, most of it spent locally on discretionary purchases, insurance renewals and mortgage extra repayments. The full CBA FY26 investor presentation lands the story: pre-provision profit rose 6 per cent to 16 billion 500 million dollars, net interest margin lifted 3 basis points to 2 point 05 per cent, and operating expenses rose 6 per cent to 13 billion 755 million dollars. Every household with a CBA transaction account is effectively paying for that expense line growth in monthly account fees and interest spreads.

Jobs Data Tomorrow: The Number That Sets the RBA Tone

The Australian Bureau of Statistics releases the July Labour Force Survey tomorrow Friday 14 August 2026 at 11:30am AEST, per the ABS Labour Force calendar. June printed at 4 point 4 per cent unemployment (unrounded 4 point 35 per cent), 76,000 more people employed month on month and participation at a one year high of 67 point 0 per cent. Trading Economics forecasts July at 4 point 5 per cent, up 0 point 1 percentage point.

The consequence chain for Australian shopper households runs through interest rates. Two days ago the RBA held the cash rate at 4 point 35 per cent but Governor Bullock struck a hawkish tone, warning it was “quite possible we might need to go” and that “interest rates might need to stay high for longer”. Swap markets priced a 50 per cent chance of a November hike overnight. If July prints AT OR ABOVE 4 point 5 per cent, weakening jobs momentum removes wage inflation pressure and pushes the November hike odds materially lower. If July prints BELOW 4 point 4 per cent with continued strong employment growth, the RBA’s hawkish stance converts into a real November hike and 3 point 3 million mortgaged households face a fourth rate rise this year. That is why retailers are running some of the deepest winter clearance markdowns of the year in the final 24 hours before spring floor rolls out Friday. Margin pressure is being priced today.

Fuel Day 11: At or Through the Retail Peak

Today is Day 11 of full fuel excise restoration. Petroleum tax jumped from 20 point 6 cents per litre in April to June, to 36 point 6 cents per litre between 1 July and 2 August (partial), to the full 53 point 7 cents per litre from 3 August, per the Australian Taxation Office. The ACCC 22nd weekly fuel price monitoring report to 5 August shows 5-city retail petrol at 207 point 5 cents per litre and diesel at 246 cents per litre, with capital city retail petrol 37 cents per litre above pre-conflict levels and diesel 71 cents per litre above pre-conflict, per FuelPlan.gov.au. The ACCC 23rd weekly report is due today or tomorrow and will confirm whether the retail petrol cycle peaked Wednesday, Thursday or Friday. RACQ’s Ian Jeffreys forecast peak within 10 days of full restoration, which is today.

Thursday tactical actions for Australian drivers. First, before you leave the driveway check Fuel Check NSW, FuelWatch WA, FuelCheck TAS, MyFuel NT, MotorMouth or PetrolSpy. The cheapest to most expensive gap in metro Sydney remains at 60 cents per litre. Second, if your vehicle handbook allows a grade drop from Premium 98 to U91 or E10, NRMA data has the grade spread at a record 26 point 5 cents per litre. On a 55-litre fill that is 14 dollars 60 cents saved per tank. Third, lock a 7-day price with 7-Eleven Fuel Lock before Friday morning. On a peak week a 20 cent per litre gap on 55 litres saved is 11 dollars per fill. If the ACCC 23rd weekly confirms Thursday or Friday as peak, tomorrow’s fills are the last high fills before the retail cycle begins its slow descent.

Retail Electricity Notes: AGL and Origin FY26

Yesterday the two big-two energy retailers delivered FY26 results. AGL Energy landed underlying EBITDA of 2 point 1 billion dollars (up 2 per cent), underlying NPAT of 631 million dollars (down 2 per cent), statutory NPAT of 756 million dollars, and operating free cash flow of 850 million dollars (up 60 per cent). Final dividend of 26 cents per share fully franked brings the FY26 total to 50 cents, up 4 point 2 per cent on FY25. AGL cited strong operational performance, disciplined capital allocation and battery growth offsetting mild winter volatility, per Investing.com’s read of the AGL FY26 slides. Origin Energy also reported yesterday with statutory profit of 557 million dollars for the first half, underlying EBITDA of 1 billion 589 million dollars, and an interim dividend of 30 cents per share fully franked per the Origin H1 26 earnings call transcript. Origin upgraded Energy Markets EBITDA guidance to 1 point 55 to 1 point 75 billion dollars.

For Australian shopper households the useful takeaway is not the dividend, it is the market signal. Both AGL and Origin are guiding for continued strong retail electricity margins driven by higher wholesale costs passed through in default market offers, but neither is aggressively cutting bills. The best household strategy remains identical to the fuel playbook: shop the plan every 90 days on the government price comparison sites (Energy Made Easy for NSW, QLD, SA, TAS, ACT; Victorian Energy Compare for VIC), and switch when the introductory discount rolls off. The average household saves 300 to 500 dollars per year on electricity by switching every 12 months.

Thursday Top 5 Deals

1Today’s Top
Discount
MossmanMossmanWomen's WearUp to 70 per cent off Mossman: dresses, knits, blouses, tops, pants, coats and accessories from the Melbourne based Australian womens contemporary fashion label founded by Melissa Trethowan, with Afterpay, Zip and free Australia wide shipping over 100 dollars.70%OFF
2HallensteinsHallensteinsMen's WearUp to 50 per cent off Hallensteins: mens tees, hoodies, shirts, jeans, chinos, jackets, knits and accessories from the New Zealand and Australia based mens fashion retailer with local Australian fulfilment, Afterpay, Zip and free Australia wide shipping over 80 dollars.50%OFF3Healthy LifeHealthy LifeHealth & BeautyUp to 50 per cent off Healthy Life: vitamins, supplements, protein powders, superfoods, natural skincare, organic pantry and wellness essentials from the family owned Australian health retailer since 1974, with Afterpay, Zip and free Australia wide shipping over 100 dollars.50%OFF4MacpacMacpacOutdoor & CampingUp to 50 per cent off Macpac: down jackets, thermals, hiking pants, base layers, tents, sleeping bags and outdoor gear from the New Zealand and Australia based technical outdoor brand since 1973 with a strong Australian retail footprint, Afterpay and free shipping over 100 dollars.50%OFF5Merchant 1948Merchant 1948FootwearUp to 50 per cent off Merchant 1948: leather boots, ankle boots, brogues, loafers, sneakers and accessories from the New Zealand and Australia based independent footwear specialist since 1948 with Australian retail stores and Afterpay, free Australia wide shipping over 150 dollars.50%OFF
Every store in Thursday’s Top 5 is Australian owned or locally fulfilled. Every discount was verified against the store’s own live sale page this morning. None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Every product ships from an Australian warehouse and is backed by the Australian Consumer Law. Mossman leads today at up to 70 per cent off dresses, knits, blouses, tops, pants and coats from the Melbourne based Australian womens contemporary fashion label founded by Melissa Trethowan. Hallensteins follows at up to 50 per cent off mens tees, hoodies, shirts, jeans, chinos and jackets from the New Zealand and Australia based mens fashion retailer with local Australian fulfilment. Healthy Life at up to 50 per cent off delivers vitamins, supplements, protein powders, superfoods, organic pantry and wellness essentials from the family owned Australian health retailer since 1974. Macpac at up to 50 per cent off runs deep on down jackets, thermals, hiking pants, base layers, tents and sleeping bags from the New Zealand and Australia based technical outdoor brand since 1973. Merchant 1948 at up to 50 per cent off closes the Top 5 with leather boots, ankle boots, brogues, loafers and sneakers from the New Zealand and Australia based independent footwear specialist since 1948.

Other Deals Worth A Look

Beyond the Top 5, a handful of other Australian owned or locally fulfilled retailers are worth a Thursday scroll. MyHouse (today’s Top 6 ticker pick) holds up to 50 per cent off homewares, bedding, bath, kitchen and decor from the Australian family owned homewares brand since 1979. P.E Nation at 30 per cent off delivers technical activewear, hoodies, joggers and tees from the Sydney founded contemporary activewear label. Veronika Maine continues at 30 per cent off tailoring, dresses and coats from the Sydney founded contemporary womens label. All Australian owned or locally fulfilled, all backed by the Australian Consumer Law.

Week Ahead

Three dates matter for Australian shopper wallets across the rest of this week. Thursday 13 August 9:15am AEST: Telstra Group FY26 full year result, watch buyback extension, postpaid ARPU direction and dividend size (Intelligent Investor forecast 19 cents fully franked). Friday 14 August 11:30am AEST: ABS Labour Force Survey for July release. Trading Economics forecast 4 point 5 per cent unemployment, up 0 point 1 percentage point. Friday 15 August: retailer spring stock transition window OPENS at major fashion, footwear and homewares categories, closing the winter clearance window. Tuesday 19 August: CBA ex dividend date, 5 dollars 5 cents fully franked payout hits accounts on 29 September.

Our Take

Thursday 13 August is the day the reporting-season baton passes from bank to telco, with Telstra FY26 at 9:15am AEST setting the tone for the rest of the week. Yesterday CBA banked 11 billion dollars cash NPAT and locked in a 5 dollars 5 cents fully franked dividend, but shares still fell 0 point 6 per cent to 172 dollars 87 cents at 28 times price to earnings: the message is that the growth story is priced. Tomorrow’s July jobs data at 11:30am AEST is the single biggest data drop this week for the mortgage repayment outlook. Fuel remains the sharpest weekly wallet drag, 5-city petrol at 207 point 5 cents per litre with today or Friday the likely retail peak. This is the FINAL FULL winter clearance day at Australian retailers. From tomorrow Friday 15 August floor space transitions to spring, and today’s headline discounts on remaining winter stock are the deepest and last full-choice window of the year. If a winter jacket, boots, thermals or a heavier knit is on the wardrobe list, today is the day.

That is exactly why It’s On Sale exists. We track 35,000 Australian stores and 45,000 live sale products, every retailer Australian owned or locally fulfilled, every promotion audited daily against the store’s own price history. No trial traps, no hidden fees, no offshore marketplaces dressed up as a local brand. Today’s Sales shows every store currently running a discount in one place. The AI search reads the way real shoppers ask (try “winter coat clearance” or “leather boots on sale”). None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Browse Today’s Sales this Thursday morning to hit the final winter clearance day at Australian retailers who stand behind the ticket and the Australian Consumer Law.

CommBank FY26 result and RBA hawkish hold - Wednesday 12 August 2026

CommBank FY26 Result at 9:30am, RBA Hawkish Hold, Fuel Day Ten Peak. | It s On Sale Daily Brief, 12 August 2026

Wednesday, mid-week and it is bank result day. Commonwealth Bank of Australia releases its FY26 full year result at 9:30am AEST this morning: cash net profit after tax around 10 billion 980 million dollars (up 7 per cent), statutory NPAT 10 billion 910 million dollars (up 8 per cent), and a full year dividend of 5 dollars 5 cents fully franked, up 4 per cent on the prior year. Ex dividend date is 19 August, record date 20 August, payment 29 September. Yesterday the RBA held the cash rate at 4 point 35 per cent, but Governor Bullock struck a HAWKISH tone at her 3:30pm press conference: she personally thought it “quite possible” rates need to go up again, ruled out near term cuts, and warned “interest rates might need to stay high for longer”. Australian swap markets responded fast: pricing now shows a 50 per cent chance of a November hike and 80 per cent chance of a move by early 2027. Fuel Day 10 today, at or near the retail peak: ACCC 23rd weekly monitoring report expected today or Thursday, 5 city petrol 207 point 5 cents per litre, diesel 246 cents per litre. Unemployment for July drops Thursday 14 August at 11:30am AEST with a Trading Economics forecast of 4 point 5 per cent (previous 4 point 4 per cent). Today’s Top 5 opens with Decjuba at up to 70 per cent off dresses, knits, tops and denim from the Melbourne founded womens fashion brand, and Colette Hayman at up to 69 per cent off handbags, jewellery and accessories from the Sydney based Australian accessories label since 1994.

CommBank FY26 Result Landing at 9:30am AEST

Commonwealth Bank of Australia releases its FY26 full year result to the ASX at 9:30am AEST this morning, per the CBA financial calendar. Wire-service coverage from ABC Business live blog shows statutory net profit after tax at 10 billion 910 million dollars, up 8 per cent on FY25, with cash profit at 10 billion 980 million dollars, up 7 per cent, per Andrew Robertson at ABC News on 12 August. The board has declared a full year dividend of 5 dollars 5 cents per share fully franked, a 4 per cent increase on FY25’s 4 dollars 85 cents, ahead of IG’s 4 August preview forecast of 5 dollars 5 cents from Chris Beauchamp at IG. The interim dividend was 2 dollars 35 cents, meaning today’s final dividend is 2 dollars 70 cents fully franked (interim 2 dollars 35 cents plus final 2 dollars 70 cents equals 5 dollars 5 cents).

What Australian shopper households should watch beyond the dividend headline. First, home loan impairment provisioning: any material increase signals loan-book stress and household budget pressure that will feed into discretionary spending over the next 6 months. Second, deposit growth and household savings ratios, which have been narrowing as fuel and utilities absorb more of the weekly budget. Third, credit card and buy-now-pay-later balances, indicators of household refinancing stress. Ex dividend date is Tuesday 19 August 2026, record date 20 August, DRP election deadline 21 August, payment 29 September, per Tristan Harrison at Motley Fool Australia. Approximately 800,000 retail shareholders receive the payout, most of them Australian households who spend a meaningful share of it locally in the September quarter.

RBA Hawkish Hold: Bullock Warns Rates Could Go Higher

Yesterday at 2:30pm AEST the Reserve Bank of Australia’s Monetary Policy Board voted unanimously to hold the cash rate at 4 point 35 per cent for a second consecutive meeting, per the RBA. The market expected a straight hold with dovish language and easing forward guidance. Instead, Governor Michele Bullock delivered one of the most HAWKISH press conferences of her tenure. Wayne Cole at Reuters via Duke FM reported her exact words: “personally, I think it is quite possible we might need to go, but we will wait and see what the data tells us”. Bullock also confirmed the Board actively DISCUSSED raising rates at this meeting.

Peter Hannam at The Guardian on 11 August reported the RBA “threatened to hike again if needed” as it warned falling house prices would slow income growth. The quarterly Statement on Monetary Policy for August 2026 now projects inflation will not return to the middle of the 2 to 3 per cent target range until early 2028, a later date than the prior forecast. Eight signal quotes from Bullock’s press conference were captured by OrbitRemit’s post decision analysis: “near term cut in rates does not align with board’s thinking”, “interest rates might need to stay high for longer”, “progress on inflation has been slow for a year now”, “still risk inflation takes too long to return to target”, “high degree of uncertainty”.

The market shift was fast. Overnight swap pricing moved from a 4 per cent hike probability priced Monday to a 50 per cent chance of a hike at the November meeting and 80 per cent likelihood of a move by early 2027. ANZ’s head of Australian economics Adam Boyton, quoted by Michael Janda at ABC News, said “our expectation is the cash [rate] has peaked although there [is] a risk of a final increase in November”. For Australian shopper households: the “hold gives me breathing room” narrative is dead. The 3 point 3 million mortgaged households now face a genuine 50-50 coin flip on a fourth rate hike this year, driving a more cautious posture on discretionary spending for the rest of Q3 and into Christmas. That is why retailers are running record final winter clearance markdowns this week: margin pressure now has a name.

Fuel Day 10: At or Near Peak

Today is Day 10 of the fuel excise restoration. Petroleum tax jumped from 20 point 6 cents per litre in April to June, to 36 point 6 cents per litre from 1 July to 2 August (partial restoration), to the full 53 point 7 cents per litre from 3 August, per the Australian Taxation Office. The ACCC 22nd weekly fuel price monitoring report (data to 5 August) shows 5-city retail petrol at 207 point 5 cents per litre and diesel at 246 cents per litre, with capital city retail petrol still 37 cents per litre above pre-conflict levels and diesel 71 cents per litre above pre-conflict, per FuelPlan.gov.au. The ACCC 23rd weekly report is due today or Thursday, and will confirm whether Wednesday or Thursday marks the retail peak (RACQ’s Ian Jeffreys forecast peak within 10 days of full restoration, meaning today or Thursday).

Wednesday tactical actions for Australian drivers. First, before you leave the driveway check Fuel Check NSW, FuelWatch WA, FuelCheck TAS, MyFuel NT, MotorMouth or PetrolSpy. The cheapest to most expensive gap in metro Sydney remains at 60 cents per litre. Second, if your vehicle handbook allows a grade drop from Premium 98 to U91 or E10, NRMA data has the grade spread at a record 26 point 5 cents per litre. On a 55-litre fill that is 14 dollars 60 cents saved. Third, lock a 7-day price with 7-Eleven Fuel Lock before Thursday morning. On a peak week a 20 cent per litre difference on 55 litres is 11 dollars. If today’s ACCC report confirms peak, tomorrow’s fills are the last ones to top up before the retail cycle begins its slow descent.

Unemployment for July Drops Thursday at 11:30am

The Australian Bureau of Statistics releases the July Labour Force Survey tomorrow Thursday 14 August 2026 at 11:30am AEST, per the ABS Labour Force calendar. June printed at 4 point 4 per cent unemployment (unrounded 4 point 35 per cent), 76,000 more people employed month on month, and participation at a one year high of 67 point 0 per cent, per Wayne Cole at Reuters on 23 July. Trading Economics forecasts July at 4 point 5 per cent, up 0 point 1 percentage point.

What this means for the RBA path and household budgets. If July prints AT OR ABOVE forecast (4 point 5 or higher), it strengthens the case that the hawkish hold Bullock delivered yesterday will convert into an actual hold through November, because a weakening jobs market removes labour cost inflation pressure. If July prints BELOW forecast (4 point 4 or lower with strong employment growth), it validates the RBA’s continued tightening bias and increases the odds of a November hike materially. The July print is genuinely the most important economic data drop this week for the household mortgage repayment outlook.

Wednesday Top 5 Deals

Every store in Wednesday’s Top 5 is Australian owned or locally fulfilled. Every discount was verified against the store’s own live sale page this morning. None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Every product ships from an Australian warehouse and is backed by the Australian Consumer Law. Decjuba leads today at up to 70 per cent off dresses, knits, tops, jeans, jackets and coats from the Melbourne founded Australian womens fashion brand launched in 2008 by Tania Austin. Colette Hayman follows at up to 69 per cent off handbags, jewellery, belts, hats and sunglasses from the Sydney based Australian womens accessories brand since 1994. Academy Brand at up to 60 per cent off delivers mens tees, shirts, chinos, denim, jackets and knits from the Sydney founded Australian mens fashion label launched in 2006. Myer at up to 60 per cent off holds a full department store range including womens and mens fashion, kids apparel, homewares, beauty, footwear and small appliances from the iconic Australian department store founded in Bendigo in 1900. Robert Gordon at up to 60 per cent off closes the Top 5 with handmade ceramic dinnerware, mugs, bowls and jugs crafted in the Dandenong Ranges since 1980 from the Australian family owned pottery.

Other Deals Worth A Look

Beyond the Top 5, a handful of other Australian owned or locally fulfilled retailers are worth a Wednesday scroll. Australian Leather (today’s Top 6 ticker pick) holds up to 50 per cent off UGG boots, slippers, sheepskin gloves and accessories from the Sydney founded family owned Australian sheepskin brand since 1988. Veronika Maine continues at 30 per cent off tailoring, dresses and coats from the Sydney founded contemporary womens label. MyHouse continues its up to 50 per cent off homewares run. Williams Shoes is at 30 per cent off leather boots and business footwear. All Australian owned or locally fulfilled, all backed by the Australian Consumer Law.

Week Ahead

Three dates matter for Australian shopper wallets across the rest of this week. Wednesday 12 August 9:30am AEST: Commonwealth Bank FY26 full-year result, dividend size (5 dollars 5 cents fully franked declared, watch impairment provisioning for household stress signals), and Rio Tinto plus Northern Star Resources reporting. Thursday 14 August 11:30am AEST: ABS Labour Force Survey for July release. TE forecast 4 point 5 per cent, up 0 point 1 percentage point. Friday 15 August: retailer spring stock transition window OPENS at major fashion, footwear and homewares categories, closing the winter clearance window.

Our Take

Wednesday 12 August is the day the RBA yesterday’s hawkish shock lands on household spending decisions. Overnight swap pricing repriced from 4 per cent to 50 per cent hike probability at the November meeting, and 3 point 3 million mortgaged households are watching. CBA’s FY26 result this morning delivers 5 dollars 5 cents fully franked to approximately 800,000 retail shareholders, but the impairment provisioning line matters more for the broader household spending outlook. Fuel remains the sharpest weekly wallet drag, 5-city petrol at 207 point 5 cents per litre with today or Thursday the likely peak of the retail cycle, and the U91 to Premium 98 grade spread at a record 26 point 5 cents per litre. Thursday’s July jobs data will determine whether the RBA’s hawkish stance holds through November or converts into an actual hike. This is the third-last full discount week on winter apparel, boots, thermals, coats, homewares and small appliances at Australian retailers. From Friday 15 August, floor space transitions to spring, and today’s headline discounts on remaining winter stock are among the deepest of the year.

That is exactly why It’s On Sale exists. We track 35,000 Australian stores and 45,000 live sale products, every retailer Australian owned or locally fulfilled, every promotion audited daily against the store’s own price history. No trial traps, no hidden fees, no offshore marketplaces dressed up as a local brand. Today’s Sales shows every store currently running a discount in one place. The AI search reads the way real shoppers ask (try “winter coat clearance” or “ceramic dinner set”). None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Browse Today’s Sales this Wednesday morning to hit the final winter clearance week at Australian retailers who stand behind the ticket and the Australian Consumer Law.

It's On Sale Daily Brief Issue 72 hero image, 11 August 2026

RBA Decision at 2:30pm, NAB Business Print at 11:30am, Fuel Day Nine. | It s On Sale Daily Brief, 11 August 2026

Tuesday, decision day. The Reserve Bank of Australia’s Monetary Policy Board announces the August cash rate call at 2:30pm AEST this afternoon after its two-day meeting. All 37 economists in a Reuters poll forecast a hold at 4 point 35 per cent, market pricing puts the hike probability at just 4 per cent, and all four major Australian banks are aligned on hold for the first time this year. Governor Michele Bullock’s press conference follows at 3:30pm alongside the quarterly Statement on Monetary Policy with updated forecasts for growth, inflation, unemployment and wages. Before the rate call, Bullock testifies to the House of Representatives Standing Committee on Economics at 9:30am AEST, then NAB Business Confidence for July releases at 11:30am AEST with a Trading Economics forecast of negative 6 (previous negative 5, Roy Morgan already at record-low 76). Fuel Day 9: FuelNow tracks 35 per cent of 7,129 stations at full 17 point 6 cent passthrough, median station 14 cents above late July, peak still 2 to 4 days away. Commonwealth Bank FY26 full-year result tomorrow, IG forecasts a final dividend of 2 dollars 65 cents fully franked. Today’s Top 5 opens with Princess Polly at up to 80 per cent off dresses, tops, jeans and coats from the Gold Coast founded Australian womens fashion brand, and Baku Swimwear at up to 70 per cent off bikinis, one pieces and resort wear from the Sydney based Australian swim label since 1998.

RBA Decision Day: 2:30pm AEST

The Reserve Bank of Australia’s Monetary Policy Board announces its August cash rate decision at 2:30pm AEST today after wrapping its two-day meeting. According to Wayne Cole at Reuters via Investing Live on 6 August 2026, all 37 economists surveyed forecast a hold at 4 point 35 per cent. 27 of the 36 respondents see no change through end-December. Interbank futures agree: CommSec’s Week Ahead has the hike probability at just 5 per cent, down from a live 30 per cent probability three weeks ago before the softer 30 July June-quarter CPI print (headline 3 point 8 per cent, trimmed mean 3 point 6 per cent). All four majors are now aligned on hold, per PolicyRix on 4 August: Westpac dropped its August hike call within a day of the CPI release.

The real event this afternoon is not the rate call. It is Governor Michele Bullock’s 3:30pm AEST press conference and the accompanying quarterly Statement on Monetary Policy, which delivers a full forecast round with updated growth, inflation, unemployment and wage projections. Bullock’s 28 July Anika Foundation speech maintained explicit tightening bias, warning that the Board “is prepared to act as required, including by increasing the cash rate target further if required”. The question this afternoon is whether the language walks back to a neutral monitoring stance. First rate cut consensus across all four majors remains 2027: NAB sees June 2027, ANZ September 2027, CBA mid-2027, Westpac August 2027. Household shopper impact: if the hold lands, mortgage variable rates near 6 point 65 per cent stay locked in for another 6 weeks minimum. Sarah Farnsworth at The Sydney Morning Herald on 10 August reports the ASX slid 0 point 3 per cent Monday and is set to dip further on RBA day, with 3 point 3 million mortgaged households waiting on the result.

NAB Business Confidence for July at 11:30am AEST

Trading Economics confirms NAB Business Confidence for July releases at 11:30am AEST today, hours before the RBA call. June printed at negative 5 (up 9 points from May’s negative 14) and the Trading Economics forecast for July is negative 6. Any print worse than negative 6 confirms retailer margin compression is deepening; any print better than negative 5 signals early spring optimism. NAB’s Q2 Business Confidence, released 29 July, sat at negative 19 index points, 22 points below the long-run average, per NAB Economy and Markets. Westpac’s Week Ahead preview captures the mood in two words: “Conditions sluggish, confidence fragile”.

Roy Morgan Business Confidence for July has already printed a record-low 76, down 1 point 5 points, per Roy Morgan Research, the fourth consecutive month below 80 and the LOWEST LEVEL EVER RECORDED in the survey. A record-low 25 point 5 per cent of Australian businesses believe now is a good time to invest in growth, and confidence has fallen below 80 across all six states for the first time. The gap between improving household mood (ANZ-Roy Morgan Consumer Confidence at 74 point 7 early August, up 3 point 5 points) and record-low business mood is the pressure squeezing retail margins right now, and that pressure is landing directly on final-winter clearance markdowns today.

Bullock Testifies to Parliament at 9:30am

Before the rate decision, Governor Michele Bullock testifies to the House of Representatives Standing Committee on Economics at 9:30am AEST today per Westpac IQ’s 10 August Week Ahead. This is the traditional biannual appearance and typically runs 3 hours with questions from committee members across all parties. Expect probing on the persistence of services inflation, the labour market at 4 point 3 per cent unemployment, household spending resilience (June retail up 0 point 8 per cent month on month, double Westpac forecast), and the credibility of the Board’s continued tightening bias when all four majors have priced hold through year-end. Bullock’s language pattern this morning will pre-signal the tone of the 3:30pm press conference.

What shoppers should watch. If Bullock walks back the tightening bias to a genuinely neutral stance, mortgage market pricing shifts earlier cuts into late 2026, which would put marginal upward pressure on discretionary spending in the November-December Christmas quarter. If she holds the hawkish line, retailers price the current final-winter clearance window as the last discount opportunity before spring stock lands from Friday 15 August. The clearance markdowns Australian shoppers see today are being set with that outcome in mind.

Fuel Day Nine: FuelNow Tracker Live

Fuel excise restoration Day 9. The FuelNow live tracker (updated 11 August 2026) reports the full 17 point 6 cent per litre passthrough is now priced in at 35 per cent of 7,129 monitored stations, with the median station sitting 14 cents per litre above its own late-July price. Diesel: 44 per cent of stations at full passthrough, median +16 point 5 cents per litre. ACCC’s 22nd weekly fuel monitoring report puts the 5-city retail petrol average to 5 August at 208 cents per litre (+7 per cent week on week) and diesel at 247 cents per litre (+6 per cent week on week), per FuelPlan.gov.au. The next ACCC weekly report drops today or tomorrow (the 23rd weekly monitoring update). RACQ’s Ian Jeffreys forecasts peak within 10 days of restoration, meaning peak lands somewhere between today and Friday 13 August. So peak is 2 to 4 days away.

Tuesday tactical actions. First, before you leave the driveway check Fuel Check NSW, FuelWatch WA, FuelCheck TAS, MyFuel NT, MotorMouth or PetrolSpy. The cheapest-to-most-expensive gap in metro Sydney remains at 60 cents per litre. Second, if your vehicle handbook allows a grade drop from Premium 98 to U91 or E10, NRMA data has the grade spread at a record 26 point 5 cents per litre. On a 55-litre fill that is 14 dollars 60 cents saved. Third, if you can lock a 7-day price with 7-Eleven Fuel Lock, do it before Wednesday morning. On a peak week a 20 cent per litre difference on 55 litres is 11 dollars.

CommBank FY26 Result Tomorrow

Commonwealth Bank of Australia releases its FY26 full-year result at 9:30am AEST Wednesday 12 August, per the CBA financial calendar. The 1H26 interim dividend was 2 dollars 35 cents fully franked, up 4 per cent on 1H25. IG’s FY26 earnings preview on 4 August forecasts a final dividend of approximately 2 dollars 65 cents fully franked, taking the FY26 total to around 5 dollars 05 cents (up from 4 dollars 85 cents PCP). Ex-dividend date is 19 August 2026, record date 20 August, payment date 29 September 2026.

What Australian shopper households should watch beyond the dividend headline. First, mortgage impairment guidance for the 3 million CBA home-loan households: any deterioration in loan-book quality or provisioning signals stress that discretionary spending would feel. Second, retail deposit growth (the household savings buffer). Third, credit card and buy-now-pay-later balance trends. CBA does not touch itsonsale.com.au deals directly, but the household budget signals in the FY26 report shape retailer pricing decisions for the September-November lead-up to Christmas.

Tuesday Top 5 Deals

Every store in Tuesday’s Top 5 is Australian owned or locally fulfilled. Every discount was verified against the store’s own live sale page this morning. None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Every product ships from an Australian warehouse and is backed by the Australian Consumer Law. Princess Polly leads today at up to 80 per cent off dresses, tops, jeans, knits, coats, activewear and shoes from the Gold Coast founded Australian womens fashion brand launched in 2010. Baku Swimwear follows at up to 70 per cent off bikinis, one pieces, resort wear and cover ups from the Sydney based Australian swim label since 1998. Gazman at up to 60 per cent off delivers mens shirts, tailoring, chinos, knitwear, jackets and accessories from the Australian owned mens fashion brand since 1975. Graham’s Jewellers at up to 60 per cent off holds engagement rings, wedding bands, diamond jewellery, watches and gifts from the Australian family owned jeweller since 1949. Telstra at up to 50 per cent off closes the Top 5 with mobile plans, prepaid phones, home internet bundles, smart home devices and entertainment plans from Australia’s largest telecommunications company since 1901.

Other Deals Worth A Look

Beyond the Top 5, a handful of other Australian owned or locally fulfilled retailers are worth a Tuesday scroll. General Pants (today’s Top 6 ticker pick) holds up to 40 per cent off streetwear, denim, sneakers, tees and outerwear from the Sydney founded Australian youth fashion retailer since 1972. Veronika Maine continues at 30 per cent off tailoring, dresses and coats from the Sydney founded contemporary womens label. MyHouse continues its up to 50 per cent off homewares run. Williams Shoes is at 30 per cent off leather boots and business footwear. All Australian owned or locally fulfilled, all backed by the Australian Consumer Law.

Week Ahead

Four dates matter for Australian shopper wallets across the rest of this week. Tuesday 11 August 9:30am AEST: Governor Bullock testifies to the House of Representatives Standing Committee on Economics. 11:30am AEST: NAB Business Confidence for July release. 2:30pm AEST: RBA cash rate decision, priced at 96 per cent hold, followed by Governor Bullock’s 3:30pm press conference and the quarterly Statement on Monetary Policy. Wednesday 12 August 9:30am AEST: Commonwealth Bank FY26 full-year result and dividend announcement, watch the mortgage-book impairment guidance and the final dividend size (IG forecasts 2 dollars 65 cents fully franked). Thursday 13 August 11:30am AEST: unemployment data for July release (last was 4 point 3 per cent). Between Friday 15 August and Wednesday 20 August: retailer spring stock transition begins across major fashion, footwear and homewares categories, closing the winter clearance window.

Our Take

Tuesday 11 August is the pivot day. The RBA holds at 2:30pm this afternoon, all four majors aligned, 96 per cent priced. That removes household mortgage anxiety for another 6 weeks and gives shopper confidence a marginal lift. Business confidence, meanwhile, is at record lows across all six states, and retailer margin pressure is producing genuinely deep final-winter clearance today. Fuel remains the sharpest weekly wallet drag, 5-city petrol averaging 208 cents per litre with peak 2 to 4 days away and the U91 to Premium 98 grade spread at a record 26 point 5 cents per litre. CommBank’s FY26 result tomorrow morning delivers the last major household-budget signal before spring stock lands from Friday. This is the last full discount week on winter apparel, boots, thermals, coats, homewares and small appliances at Australian retailers. From Friday, floor space transitions to spring, and today’s headline discounts on remaining winter stock are the deepest of the year.

That is exactly why It’s On Sale exists. We track 35,000 Australian stores and 45,000 live sale products, every retailer Australian owned or locally fulfilled, every promotion audited daily against the store’s own price history. No trial traps, no hidden fees, no offshore marketplaces dressed up as a local brand. Today’s Sales shows every store currently running a discount in one place. The AI search reads the way real shoppers ask (try “winter coat clearance” or “swimwear sale”). None of it is Temu, Shein, AliExpress, Wish or any offshore marketplace dressed up as a local brand. Browse Today’s Sales this Tuesday morning to hit the final winter clearance week at Australian retailers who stand behind the ticket and the Australian Consumer Law.